
Writer: Brittney Mayer


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

As exciting a time as college can be, it can also be a stressful one, and not simply due to the exams. Part of what makes college a less-than-carefree experience is that the average college student is typically broke. Indeed, without any real skills — that’s what you’re in college to learn, after all — the income opportunities for a college student aren’t exactly lucrative.
And a lack of income can be frustrating for more than just the obvious reasons (like living on little more than mac and cheese). Without income, it can also be harder to get and build credit, which may leave you at a financial disadvantage after graduation.
Thankfully, one skill you picked up in college can really help here: research. Student-friendly ways to build credit are out there, and once you know where to look, they’re much easier to spot.
-
Navigate This Article:
Students with No Income May Face Barriers to Credit
Once upon a time, a stack of bright, shiny credit card offers would grace your mailbox just about the moment you turned 18, opening the world of consumer credit to young people everywhere. For better or worse, those days are history — and the CARD Act of 2009 is responsible for their demise.
Designed to enact a range of protections for consumers, such as mandating rate increase alerts, the CARD Act also introduced new restrictions on when and how credit card companies can send offers to young people.
One example is the minimum age for obtaining a credit card, which was originally set at 18. Thanks to the CARD Act, individual credit card applicants must be at least 21 years of age unless they meet specific conditions.
In particular, consumers between the ages of 18 and 21 must have a verifiable income source — beyond that monthly “stipend” from your folks — to qualify for a credit card. This is to ensure you have a reasonable means of paying down your balance, as racking up debt with no way to repay it isn’t good for you or your credit card issuer.
One traditional way to avoid the income requirement for credit card applicants under the age of 21 (or, really, any age, as most issuers will prefer you to have an income) is to apply with a qualified cosigner.
However, the vast majority of major credit card issuers no longer offer co-signing as an option.
| Credit Card Issuer | Co-Signer Allowed? |
|---|---|
| American Express | No |
| Bank of America | No |
| Barclays | No |
| Capital One | No |
| Chase | No |
| Citi | No |
| Discover | No |
| U.S. Bank | No |
| Wells Fargo | No |
Students who don’t have any income may want to consider becoming an authorized user on a credit card account owned by someone with an income and an established credit history. Authorized users can receive their own credit card and make purchases but they don’t control any other aspects of the account.
Another bonus is that many issuers will report timely payments to the credit bureaus for both the account holder and the authorized user. That can be a great way for students to build credit they can use to qualify for better rates and terms once they start having an income of their own.
Student Cards Can Be Easier to Obtain
While you can’t even think about getting your own credit card without an income or cosigner until you turn 21, obtaining a new line of credit won’t be a picnic at any age if you don’t have money coming in. Even with a modest income, without an established credit history, most credit card issuers will still consider you to be a risky bet.
On the plus side, a variety of issuers are willing to take that bet. With a little research, you can find a range of student-centered credit cards with flexible credit requirements that can help you start building your credit profile. You don’t have to sacrifice perks, either. Many student cards will also let you earn cash back rewards on your purchases, including our favorites below.

When comparing student cards, it’s important to understand exactly how your new card will work. This includes understanding the specific interest rates you’ll be charged, as different types of transactions may charge different rates. You’ll also want to determine any applicable fees, such as annual fees and late fees, as well as the various transaction fees, like balance transfer or foreign transaction fees.
Secured Credit Cards May Only Require a Deposit
Arguably the easiest credit card to get, secured cards require an initial deposit to open your account. That deposit acts as collateral against potential default, meaning if you become seriously delinquent (more than 180 days late), the issuer can use your deposit to cover your outstanding balance. This results in lower risk to the issuer, and, thus, looser credit requirements for the applicant.
The nature of secured cards also makes them a lower risk for cosigners, which is good because secured cards are not immune to the CARD Act requirements, so you’ll still need to show income or have a cosigner if you’re under 21. A limited credit history will be less important, however, as secured credit cards, such as the expert-rated options on our list, tend to have more flexible credit requirements — some cards won’t even require a credit check.
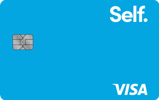
For a secured credit card, your initial deposit is more than simply collateral. The size of your deposit will also determine the size of your available credit line — i.e., your credit limit — typically at a rate of 90% to 100% of your deposit, up to the card’s maximum. If you can’t afford a large deposit initially, most cards will allow you to add to your deposit over time.
Prepaid Cards Don’t Require Approval
Offering all the shopping perks of a credit card — including the ability to make online purchases — prepaid cards aren’t actually associated with a consumer credit line, but are, instead, prepaid by the cardholder before use. Not only does this mean your lack of credit history won’t be an issue, it also means the CARD Act won’t be a problem, either — income or no income.
On top of being accepted almost anywhere credit is, prepaid cards can offer a few perks your credit card may not, including direct deposit capability. Features and fees vary from one card to the next, so take time to weigh your choices carefully. Our expert-rated picks are a helpful place to begin your search.
*Terms and conditions apply. GO2bank™ cards are issued by Green Dot Bank, Member FDIC, pursuant to a license from Visa U.S.A., Inc. Visa is a registered trademark of Visa International Service Association. Overdraft fees may apply. Click Apply Now to learn more.
*Please see site for full terms and conditions.
Additional Disclosure: Walmart MoneyCard® is a debit card offer.
The fact that prepaid cards aren’t associated with a credit line can be helpful for those with troubled or nonexistent credit profiles, but it isn’t all good news. The same way your credit has no impact on your ability to obtain a prepaid card, your prepaid card will have no impact on your credit.
In other words, prepaid cards can’t be used to establish, rebuild, or repair your credit reports or scores. So, if you’re only looking for a way to make easy purchases, a prepaid card can work. If you want purchasing power and credit-building credit reporting, stick with an unsecured or secured credit card.
Only Charge What You Can Afford to Repay
Sure, college may come with the occasional stress dream about showing up to finals in your birthday suit, but it can also be a lot of fun. Still, if you want to make the most of those years, you’ll need to put in plenty of effort along the way.
Of course, of all the lessons you’ll likely learn in college, some of the most important won’t occur within the walls of a classroom. No, some of your key discoveries will be made through trial — and through error.
You can reduce the impact of many of those hard lessons with the right bit of research, and that applies to your financial lessons, as well. As the old saying goes, “forewarned is forearmed.”
In particular, understand the importance of your credit report and score, including the factors that influence your credit score calculation. This will ensure you have the skills and knowledge to use your new card wisely, allowing you to come out of college well-prepared to face the next stage of your financial journey.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author