
Writer: John Ulzheimer


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

If you’ve done any research on how to build or rebuild your credit, you’ve undoubtedly stumbled across online forums or blogs that indicate that secured cards are a practical approach in that endeavor. As with most of these credit-building strategies, there’s a little bit of myth and truth circulating the web.
So, exactly how much will a secured card increase credit scores?
A Secured Card Doesn’t Guarantee a Specific Credit Score Increase
Consumers have lots of credit-building tools at their disposal. But if there were a trifecta of tools to help earn consumers good credit scores, it would include:
- getting a secured credit card
- becoming an authorized user on someone else’s account
- and finding a cosigner
It’s true that opening one or more secured credit cards will likely populate your credit reports with new, positive data. Paying your bill on time every month can help increase your credit score because payment history accounts for 35% of your FICO credit score.
That can certainly be helpful, especially for lenders with policies that reward you for having good information on your credit report.
But from a usage perspective, you’re limited to the credit limit established by the deposit you made with the lender. That means you don’t have a very impressive credit limit, and for good reason. You don’t want to tie up thousands of dollars of your cash simply to get a secured credit card with a larger credit limit.
Even modest use of a secured credit card can lead to unmanageable debt if you’re not careful. And, if you know anything about credit scoring models, you know they don’t reward you for having credit cards with large balances. In that respect, secured cards can work against you.
Secured Cards and Collateral
In consumer lending, the term “secured” indicates that some sort of asset was provided to back the extension of credit. The asset secures the extension of credit and, thus, helps protect the lender in cases of default.
Mortgages, home equity style loans, and auto loans are examples of secured extensions of credit. In those examples, houses and cars act as security for the lender.
When you signed all of your loan paperwork, you pledged those things as security for the lender. If you were to default on a mortgage or an auto loan, you’d lose your home or your car.
The same thing holds true for secured credit cards. But instead of pledging some physical asset, you’re pledging money.
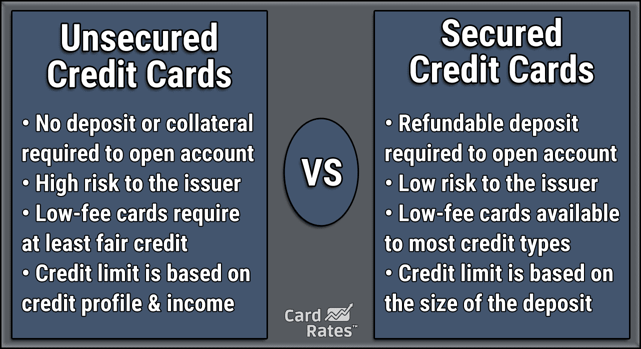
With secured credit cards, the card issuer asks you to make a deposit in exchange for a new card with a credit limit equal to or close to the amount of cash you deposited with the lender.
So, for example, if you deposited $500 with the issuer, you may get a secured card with a $500 credit limit.
If you default on a secured card, the issuer will keep your security deposit to pay your balance. It will also report the default to the credit bureaus.
You can’t argue that because you already paid them, your card was never actually late. The deposit isn’t payment for future invoices. You still have to pay your bills just as you would any other extension of credit.
Find a Card That Reports to All 3 Bureaus
One more thing to keep in mind as you consider applying for a secured credit card is whether it reports to the major credit reporting agencies.
Not all secured card issuers report their accounts to Equifax, Experian, and Transunion, the three main credit reporting agencies, because it’s not mandatory. This means you cannot force your card issuer if its policy is to report accounts to only one or two of the credit bureaus.
Secured cards that are not reported to all three of the credit bureaus have even more limited credit-building value. If an account is not on a credit report, it’s like the tree that falls in the woods. Nobody hears it, and nobody cares.
If you open one or more secured cards and the card issuer only reports to one or two credit bureaus, the card will have no value to that third credit report. That also means any scores derived from that third credit report will not and cannot consider how well you’ve managed the card because the scoring model cannot see the card.
The easy way around this is to shop for secured cards from card issuers that report to all three credit bureaus, such as:

- The secured Self Visa® Credit Card* requires no credit check or minimum score.
- Reports to all 3 major credit bureaus to establish and build credit, with free access to your credit score.
- Secure your credit line with a refundable security deposit as low as $100.**
- Deposits are returned upon account closure after settling outstanding balances.
- *The secured Self Visa® Credit Card is issued by Lead Bank, Sunrise Banks, N.A., or First Century Bank, N.A., each Member FDIC.
- **Qualification for the secured Self Visa® Credit Card is based on meeting eligibility requirements, including income and expense requirements and establishment of security interest. Criteria subject to change.
- Earn up to 10% cash back on everyday purchases
- No credit check required – 89% approval rate with zero credit risk to apply!
- Boost your credit score fast—2 out of 3 opensky® cardholders see an average increase of 47 points after 6 months
- Track your progress with free access to your FICO® score in our mobile app
- Build your credit history with reporting to all three major credit bureaus: Experian, Equifax, and TransUnion
- Seamless payments—add your card to Apple Pay, Google Pay, and Samsung Pay
- Start with just $200—secure your credit line with a refundable deposit
- Fast and easy application—apply in minutes with our mobile-first experience
- Flexible payment options—pick a due date that works for you
- More time to fund—spread your security deposit over 60 days with layaway
- Join 2 million+ cardholders who have used opensky® to build better credit!
- No annual or hidden fees, and you can earn unlimited 1.5% cash back on every purchase, every day. See if you’re approved in seconds
- Put down a refundable $200 security deposit to get at least a $200 initial credit line
- Building your credit? Using a card like this responsibly could help
- Enjoy peace of mind with $0 Fraud Liability so that you won’t be responsible for unauthorized charges
- You could earn back your security deposit as a statement credit when you use your card responsibly, like making payments on time
- Be automatically considered for a higher credit line in as little as 6 months with no additional deposit needed
- Earn unlimited 5% cash back on hotels, vacation rentals and rental cars booked through Capital One Travel
- Monitor your credit score with CreditWise from Capital One. It’s free for everyone
- Top rated mobile app
By using a card that reports to all three bureaus, you will then know for certain that you’re getting the maximum value out of opening a secured card.
Be Realistic About Credit-Building Expectations
The Fair Credit Reporting Act allows negative information to remain on your credit reports for seven and 10 years. Those who have gone through the credit rebuilding process know firsthand that it’s a long journey.
Adding a secured credit card to your credit reports doesn’t cancel the negative impact of a derogatory credit history. Secured cards are not a silver bullet. You need to be realistic with your expectations.
Adding a secured card to your credit reports can help rebuild your credit, but it can’t eliminate the impact of defaults, late payments, and collections. A secured card won’t turn your 580 FICO Score to 700 overnight.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author