
Writer: Marcie Geffner


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

Key Takeaways
One way to avoid interest while paying off credit card debt is to get a balance transfer credit card with a 0% APR promotion. Here are some of our experts’ top picks:
-
BankAmericard® credit card: Best for an extended 0% intro APR window.
-
Discover it® Chrome: Best for earning cash back and its long 0% APR promo. See rates & fees
There’s no doubt about it: Credit card interest rates are going up, and these rate hikes can hurt consumers who don’t pay off their card balances every month.
Rates can rise when the Federal Reserve hikes its benchmark federal funds rate. Consumers don’t pay this rate directly, but when it goes up, market rates — the rates consumers do pay — also tend to move higher.
In the article below, we’ll dive into important things to know — and actions to take — when interest rates rise, as well as seven options for rising credit card interest rates.
Credit Card Interest Rates Remain Near Historic Highs
The Fed’s benchmark rate is currently in the 3.75% to 4% range. But before it started hiking rates to deal with inflation in 2022-2023, the rate was near 0%.
Credit card interest rates are significantly higher than the federal funds rate because banks add a profit margin, known as the spread.
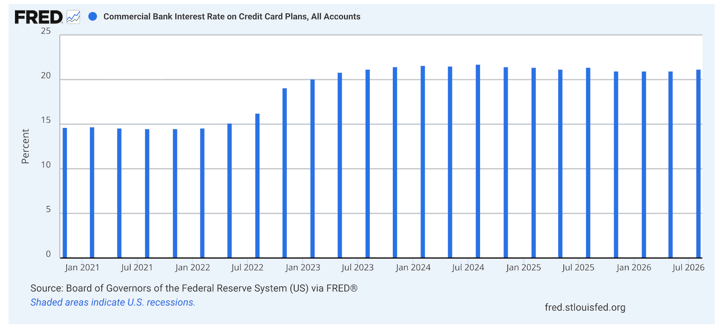
The average credit card interest rate across all accounts is now about 21%, according to Federal Reserve data.
That average doesn’t mean everyone who has a card pays 21%. In fact, the Fed data shows that average card rates for people who were charged interest were closer to 22%. And that was before this year’s rate hikes.
How much interest you’ll pay if you carry a balance depends on your credit score, your payment history, and the types of cards you have, among other factors.
“Interest rates charged vary considerably across credit card plans and borrowers, reflecting the various features of the plans and the risk profile of the cardholders,” the Fed states.
And interest rates remain in flux because the Federal Open Market Committee constantly monitors inflation, employment, and other measures of economic activity to decide when to raise (or lower) the federal funds rate.
What To Do When Your Card Rate Rises
There’s no one best thing you should do if your card’s interest rate rises. Rather, there are a variety of actions you could take, each with pros and cons.
Here are six options to consider:
1. Pay the Higher Rate
If you carry a balance and you can afford to pay the higher rate, you may want to just do so. Why? Maybe you carry a balance only rarely or only for a short time.
Maybe your balance is low, or you intend to pay it off soon. Maybe your card has low fees or a rewards program that you love.
Whatever the reason, a higher rate doesn’t necessarily mean you have to dump your card.
2. Pay off Your Balance
If you’ve been carrying a balance and your rate rises, that may be a good incentive to pay off your card to lower or eliminate your monthly interest expense.
If you never carry a balance again, you won’t be affected by your card’s higher rate.
3. Ask for a Lower Rate
If you normally carry a balance and are struggling to make your monthly card payment, you may want to call your card issuer and ask for a lower rate.
If your card company wants to keep you as a customer, it may lower your rate as a courtesy. Ask when the lower rate expires so you can revisit your options and decide what to do next.
4. Transfer Your Balance to Another Credit Card
If you have several cards and your rate rises on a card on which you carry a balance, call your card issuers and ask them about their balance transfer offers.
Find out how much you can transfer, what rate you’ll be charged, and how much the transfer will cost. We even created this handy calculator to make the process a little easier:
Some cards offer very attractive programs to entice you to transfer an existing balance.
5. Shop for a New Balance Transfer Card
If you carry a balance and don’t have another card with an attractive balance transfer offer, a higher rate may be an incentive to apply for a new balance transfer card.
When you shop for a balance transfer card, look for a low promotional rate and balance transfer fee. Some cards offer a 0% initial rate and no balance transfer fee. Ask how long your promotional rate will last and what your full rate will be when that rate expires.
Transferred balances typically don’t earn rewards, so you can make those perks a low priority when you compare cards. Here are some of our favorites:

- 0% Intro APR for 21 billing cycles for purchases, and for any balance transfers made in the first 60 days. After the Intro APR offer ends, a Variable APR that’s currently 15.24% – 26.24% will apply. A 5% fee applies to all balance transfers. Balance transfers may not be used to pay any account provided by Bank of America.
- No annual fee.
- No penalty APR. Paying late won’t automatically raise your interest rate (APR). Other account pricing and terms apply.
- This offer may not be available elsewhere if you leave this page. You can take advantage of this offer when you apply now.
Additional Disclosure: Bank of America is a CardRates advertiser.
- Get a 0% intro APR for 18 months on balance transfers and 0% intro APR on purchases for 6 months; balance transfer fee applies. Then 17.74% to 26.74% Standard Variable APR applies, based on credit worthiness
- INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300
- Earn 2% cash back at Gas Stations and Restaurants on up to $1,000 in combined purchases each quarter, automatically. You’ll still earn unlimited 1% cash back on all other purchases
- Redeem cash back for any amount
- No annual fee
- Terms and conditions apply
- $200 online cash rewards bonus after you make at least $1,000 in purchases in the first 90 days of account opening.
- Earn 6% cash back for the first year in the category of your choice. You’ll automatically earn 2% cash back at grocery stores and wholesale clubs, and unlimited 1% cash back on all other purchases. After the first year from account opening, you’ll earn 3% cash back on purchases in your choice category.
- Earn 6% and 2% cash back on the first $2,500 in combined purchases each quarter in the choice category, and at grocery stores and wholesale clubs, then earn unlimited 1% thereafter. After the 3% first-year bonus offer ends, you will earn 3% and 2% cash back on these purchases up to the quarterly maximum.
- No annual fee and cash rewards don’t expire as long as your account remains open.
- Turn daily purchases into everyday wins. Simply use your Customized Cash Rewards credit card for the things you already buy – from gifts to groceries – BofA Rewards™ members earn more cash back.
- 0% Intro APR for 15 billing cycles for purchases, and for any balance transfers made in the first 60 days. After the Intro APR offer ends, a Variable APR that’s currently 17.74% – 27.74% will apply. A 3% Intro balance transfer fee will apply for the first 60 days your account is open. After the Intro balance transfer fee offer ends, the fee for future balance transfers is 5%. Balance transfers may not be used to pay any account provided by Bank of America.
- This offer may not be available elsewhere if you leave this page. You can take advantage of this offer when you apply now.
Additional Disclosure: Bank of America is a CardRates advertiser.
- 0% Intro APR on balance transfers for 21 months and on purchases for 12 months from date of account opening. After that the variable APR will be 16.74% – 27.49%, based on your creditworthiness. Balance transfers must be completed within 4 months of account opening.
- There is an intro balance transfer fee of 3% of each transfer (minimum $5) completed within the first 4 months of account opening. After that, your fee will be 5% of each transfer (minimum $5).
- No Annual Fee – our low intro rates and all the benefits don’t come with a yearly charge.
- Buy now and pay later. Split your payment for eligible purchases of $75 or more into a fixed payment with Citi® Flex Pay.
- Get free access to your FICO® Score online.
Additional Disclosure: Citi is a CardRates advertiser.
- Earn $200 cash back after you spend $1,500 on purchases in the first 6 months of account opening. This bonus offer will be fulfilled as 20,000 ThankYou® Points, which can be redeemed for $200 cash back.
- Earn 2% on every purchase with unlimited 1% cash back when you buy, plus an additional 1% as you pay for those purchases. To earn cash back, pay at least the minimum due on time. Plus, earn 5% total cash back on hotel, car rentals and attractions booked with Citi Travel.
- Balance Transfer Only Offer: 0% intro APR on Balance Transfers for 18 months. After that, the variable APR will be 18.49% – 28.74%, based on your creditworthiness.
- Balance Transfers do not earn cash back. Intro APR does not apply to purchases.
- If you transfer a balance, interest will be charged on your purchases unless you pay your entire balance (including balance transfers) by the due date each month.
- There is an intro balance transfer fee of 3% of each transfer (minimum $5) completed within the first 4 months of account opening. After that, your fee will be 5% of each transfer (minimum $5).
Additional Disclosure: Citi is a CardRates advertiser.
You might need to call your card issuer to transfer your balance and you should continue to make your payment until the transfer is complete.
Don’t make a habit of using balance transfer cards to juggle more debt than you can afford. A better approach is to reduce your spending—radically, if necessary—until you can pay off all your card balances every month.
6. Close Your Account
Rising card rates can be a good incentive to review all your cards and make sure you’re happy with them. If you have a card that you don’t need, you can stick it in a drawer and not use it.
If it has an annual fee, you may want to call the card issuer and cancel it. Keep in mind that canceling cards can affect your credit score.
Your Interest Rate is Just One Factor to Consider
There’s no right number of credit cards that you should have. Some people manage with just a few. Others want and use dozens to maximize their rewards.
Credit card interest rates are just one factor, albeit an important one, you should consider when you choose which cards you want to apply for and use most often.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author