

Writer: Andrea Woroch


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

The coronavirus lockdown has flipped our world upside down. In addition to the health threat this virus poses, people are also suffering financially with millions losing their jobs or experiencing reduced hours and cut wages.
In fact, a recent online poll from Fortune and SurveyMonkey found that 63% of U.S. consumers are worried they won’t have enough money to pay their monthly bills.
Managing your budget in the wake of this pandemic comes down to planning. Mapping out which bills to pay now, which to postpone, and how to lower expenses can alleviate some of the financial pressure and anxiety you may be feeling right about now.
Follow this step-by-step guide to get your monthly bill payment plan in order.
1. Make a Bill Prioritization Plan
The first step to managing your bills during this economic downturn is to understand your options. Some banks and service providers are allowing customers to defer or reduce payments, so get on the phone to find out:
- who is offering what
- how long you can defer payments
- payment plan options
- if any fees or interest will be applied to your account
- how deferred payments will be reported to credit bureaus
List out all your monthly expenses and make a note next to each bill, highlighting their terms and conditions for payments during this time. From there, you can prioritize which bills to pay.
Keep in mind that some lenders may keep charging interest during a deferment, and those costs may be added to your loan balance. The tradeoff is that you could end up owing more by the time repayment resumes.
This is why it’s important to understand all the terms and conditions of postponing payments and prioritize paying those bills that will continue accruing interest, so you don’t waste more money in the long run.
For example, federal student loans will not accrue interest until September 2020, or possibly longer, so this is a bill you can confidently defer. On the flip side, private student loans will accrue interest even when you defer, so pay this bill ahead of others.
2. Analyze Recurring Expenses
Take time to go through your credit card and bank statements to pinpoint your monthly, quarterly, and annual recurring expenses to determine which ones you actually need and use, and which ones can go.
This process may help you uncover a subscription you forgot you signed up for that is costing you a few bucks each month. Even if it’s not a lot of money, it’s still a waste to spend it on something you don’t need and aren’t using.
For those nonessential services you enjoy, like a beauty sample box delivery, now may be the right time to pause them. The good news is it doesn’t have to be permanent — you can always sign back up for a favorite subscription or membership once your finances feel steadier. Thinking of it as a temporary break can make canceling a little easier.
3. Negotiate Rates on Monthly Services
Nothing bad can come from trying to negotiate your bills, so you may as well give it a try. For the best chance of securing a lower rate, run a quick online search to see what competitors in your area are offering, and use that information as leverage in your negotiating.
If the first person you get on the phone isn’t able to help, politely ask to speak with a supervisor or manager who may have more authority to adjust prices. If your negotiations still are not getting very far, consider switching providers if their rates are truly better.
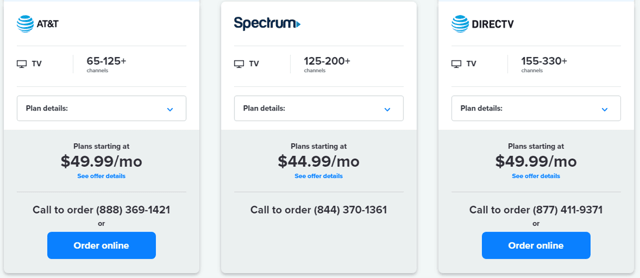
Threatening to cancel will often send you to the retention team who will work harder to keep you!
4. Shop Around for Insurance
You may have scored a great rate on your homeowners and auto insurance when you first bought your home or car, but if you haven’t touched the policy since, you may have noticed small increases to your premium over time. Now is the time to shop around to see if you can snag a better rate from a competitor.
Begin by quickly comparing insurance quotes through sites like PolicyGenius.com and Insurance.com. Just make sure you read the fine print so you’re getting the coverage you need and want.
Another trick to lowering your monthly payment is to increase your deductible. Depending on how much you increase this payment, you could significantly reduce your annual premium.
Raising your deductible means you assume more risk upfront. Be proactive and put those premium savings in a separate savings account until you reach your deductible. That way, you have the money to pay out-of-pocket costs if you have to file a claim. And, considering you aren’t driving as much right now, your chances of getting into a car accident are very low, so increasing your auto insurance deductible can squeeze some additional savings out of your monthly budget.
5. Opt for a Lower-Tiered Data Plan
If most of your time is spent at home these days because your workplace has transitioned to remote operation, chances are you really aren’t using much data. If you are using your home WiFi, why not lower your monthly plan?
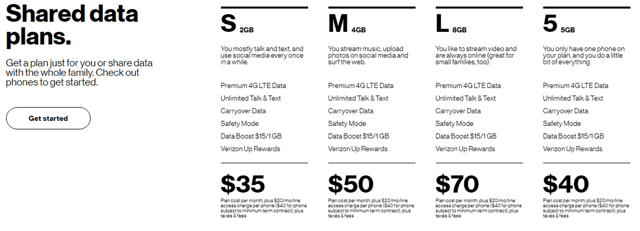
Some mobile carriers let you change your monthly plan online. If you do need to call customer service, don’t get sidetracked by bonus offers meant to keep you on your current plan. Stay focused on your main goal: lowering your monthly bill.
6. Look for Free Service Alternatives
Families have turned to video streaming services to stay entertained during the stay-at-home orders. However, you don’t have to pay more money on new subscriptions if you’re looking for new content.
Many people don’t realize that libraries offer digital access to borrow streaming content such as movies, TV shows, documentaries, audio and ebooks — all without leaving your home. If you don’t have a library card, you can usually apply right online to gain access quickly.
Otherwise, look into your mobile carrier deals. Some offer access to video streaming services with your plan. For example, Sprint provides members with a free subscription to Hulu, and T-Mobile offers a free Netflix subscription. You can view the full list of deals at whistleout.com.
7. Look for a New Credit Card
The average credit card debt per household hovers around $5,700, according to the U.S. Federal Reserve. With such a high balance, those who can’t afford to pay more than the minimum due are wasting money on interest and will struggle to dig themselves out of debt.
Now is a great time to look into new credit cards that may be offering 0% interest on balance transfers for a set time, which could be for anywhere from 12 to as much as 21 months. Here is our top-rated balance transfer card:

- 0% Intro APR for 21 billing cycles for purchases, and for any balance transfers made in the first 60 days. After the Intro APR offer ends, a Variable APR that’s currently 15.24% - 26.24% will apply. A 5% fee applies to all balance transfers. Balance transfers may not be used to pay any account provided by Bank of America.
- No annual fee.
- No penalty APR. Paying late won't automatically raise your interest rate (APR). Other account pricing and terms apply.
- This offer may not be available elsewhere if you leave this page. You can take advantage of this offer when you apply now.
Additional Disclosure: Bank of America is a CardRates advertiser.
A balance transfer buys you more time to make payments toward the actual balance without accruing additional interest and gives you more flexibility in your payments. Just make sure you read the fine print and can pay down the balance in full before the promotional date is up to avoid potential retroactive interest charges.
8. Refinance Your Mortgage
If your monthly mortgage payment isn’t giving you much flexibility in your budget to afford other expenses, look into refinancing your loan. The benchmark mortgage rates are near record lows and you could be looking at saving a whole percentage point on your interest rate.
Not only will this lower your monthly bill, but it could save you thousands of dollars in interest. When shopping around for lenders, make sure you are comparing rates and fees, and ask for a breakdown of your new payment amount plus all the loan closing costs so there are no surprises.
Credit unions typically offer better rates and lower fees, and are a good place to start looking.
9. Cash in On Clutter
If you’re spending more time at home, this can be a great opportunity to tackle long-postponed decluttering projects. Check your closets, drawers, kid’s playroom, pantry, garage, and attic to see what you can donate, toss, or sell.
From unworn clothing to gently used baby items and toys to video games and other unwanted gadgets, you could be sitting on hundreds of dollars’ worth of items that you could easily sell online.
Whether you prefer to sell the items yourself through auction sites or want cash quickly upfront, several sites make the process of cashing in on your unwanted items easy. Plus, the money you make from selling your stuff could help cover your bills over the next few months.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author