
Writer: Andrea Woroch


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

The average credit card debt per U.S. household hovers over $8,000. Although this number is shocking, it doesn’t mean you should cut up your cards and banish them from your life altogether.
In fact, when used wisely, credit cards can actually improve your financial health. From increasing your credit score to offsetting everyday costs and travel expenses, and providing additional protection for big-ticket purchases, credit cards can be valuable tools toward managing your money better.
At least a few times a year, it’s a good idea to review your credit card habits and make sure you’re doing everything you can to stay out of debt and build good credit. Here’s a quick look at the different credit card strategies you should begin using to improve your financial health.
1. Automate Payments
Missing payment deadlines from time to time may seem harmless, but credit card companies take this seemingly minor mistake seriously. And, perhaps more importantly, so do the credit reporting bureaus and scoring agencies.
To start, your tardiness will likely result in a late fee (usually $25 for the first missed payment and then $35 on average if you’ve been late on your payment within the past six months). Plus, you could get hit with a penalty interest rate of up to 29.99%, which can add a significant amount to your debt load depending on your current balance.
If your payment is more than 30 days late, it can be reported to the credit bureaus as a delinquent payment. Since your payment history is worth up to 35% of your FICO credit score, this can mean serious credit damage. Plus, late payments can stay on your credit reports — and impact your scores — for up to seven years.

Setting up automatic payments for at least the minimum due will ensure you never miss a deadline. Better yet, automate payments to cover the entire bill so you don’t start racking up a balance.
2. Pay Balances In Full
Reward cards are popular these days and make total sense to use since you can get something back for the purchases you’re making anyway. However, those who regularly carry a balance on their cards from month to month won’t truly benefit from the money-saving perks they earn.
That’s because the interest you pay on your balance ultimately dilutes the rewards. In some cases, you may be paying more in interest than you are actually receiving in cash back or travel points.
To avoid this, treat your credit card like a debit card and only charge what you can pay off in full each month. Reviewing your checking account balance on a daily basis can help deter you from overcharging.
If you absolutely must carry a balance, consider getting a credit card with an introductory APR offer. These deals can provide six months or more of 0% APR on new purchases and/or balance transfers, saving you from high interest rates for the duration of the promotional period.
3. Track Spending
Credit card spending can easily spiral out of control if you aren’t paying close attention to what you’re buying or how much you’re charging with each swipe. And keeping track of your spending means more than just glancing at your statement each month.
It’s easier than ever to track your spending, however. A number of useful mobile apps can be downloaded that can help you track your purchases, with most manual and automatic tracking options available. Some popular apps include:
- Mint
- You Need a Budget
- Mvelopes
- Personal Capital
- Spendee
Personal finance apps can pull all your credit cards into one place, making it easier to track your spending and spot areas where you may need to cut back. Regular account reviews can also help you catch incorrect charges, remember to cancel a trial membership before it renews, and flag fraudulent activity quickly.
4. Evaluate Your Card Collection
At least once a year, you should evaluate your credit card collection to ensure each and every card is pulling its weight. This can be particularly important for cards that have annual fees.
Review how you’ve used each card over the past year and figure out whether the rewards or added perks were enough to offset the annual fee. If not, it may make sense to cancel the card or downgrade to a similar no-fee option.
Additionally, consider if you actually need all of the cards you own. Although travel hackers suggest opening multiple cards to stockpile introductory bonus offers and earn free flights and hotel stays faster, some people will get themselves into trouble by carrying several cards in their wallet at the same time.
For some people, having more available credit can make overspending feel a little too easy. Too many cards can also raise the odds that you’ll miss an important due date. In the end, sticking with one or two cards that match your spending habits and rewards goals may help you avoid charging more than you can comfortably repay.
5. Know Your Card Terms
Before you sign up for a new credit card, make sure to read the fine print. An introductory APR of 0% is attractive, but it’s much more important to know what the interest rate is after the promotion ends and whether you will be charged retroactive interest on any purchases made and not paid off during that initial period.
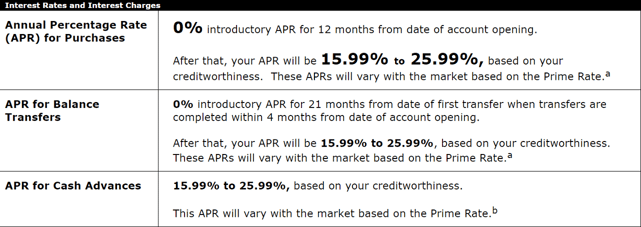
Ultimately, you want a credit card that offers a low interest rate and doing your homework can keep you from getting into a sticky situation when the promotional offer ends. You also want to check if there’s a yearly fee associated with the card, such as cash back rewards.
Although there are plenty of cards that don’t carry annual fees, those with generous programs often do. This fee, which is sometimes waived for the first year to attract new cardmembers, can range from $25 to a whopping $500 depending on the credit card.
6. Redeem Rewards
Using travel rewards to book free hotels and flights or applying cash back to your credit card statement are all smart ways to stretch your budget further. However, studies show that $16 billion in reward points go unredeemed every year.
Why? Well, consumers often hoard rewards to save up for a valuable redemption opportunity. After all, you want to make sure you’re getting something great for all those purchases you made.
But, many cardholders lose their rewards each year due to inactivity or by letting them expire. Don’t fall into this same trap.
Review your credit card rewards program details to understand exactly how you can earn and redeem rewards or what will happen to points or cash back rewards that don’t get used right away. Then, think about how you can start redeeming your rewards — perhaps to offset gift purchases, travel costs and other everyday card expenses.
7. Take Advantage of Extra Perks
Beyond the reward program your credit card offers, you may be missing out on extra perks simply because you aren’t familiar with them. In fact, many credit cards offer basic cardholder benefits like purchase and return protection, extended warranties, and rental car insurance coverage.
For example, the Chase Sapphire Preferred® Card, a popular travel card, offers primary rental car insurance. It also comes with trip delay travel insurance that can reimburse you if your flight is late or your trip is canceled for a covered reason.
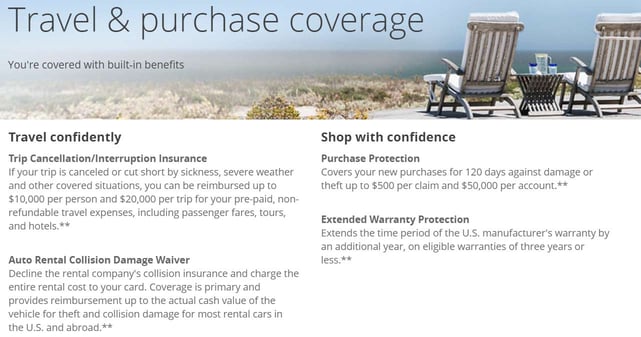
Get to know the perks your card offers, since they may let you skip insurance coverage pushed by rental car companies and costly extended warranty plans promoted by electronics retailers, helping you save money.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author