How to Use a Credit Card: 5 Ways to Do So Wisely (Sep. 2026)
Learn how to match your credit tier with the right card and use APR, rewards, and return protection more wisely.
Writer: Linsey Knerl
Linsey Knerl, Contributing Expert
Linsey Knerl is a finance author and public speaker with a passion for helping everyday families earn more and live better. Her work can be seen in Investopedia, PC Mag, The Christian Science Monitor, TIME, Wise Bread, Next Avenue, MSN Money, and numerous other leading outlets. Her expertise lies in business economics, credit scores and reports, and saving and budgeting. Linsey has shared her financial knowledge with audiences at SXSW, FinCon, and the ASJA annual NYC convention.
Lillian Guevara-Castro brings more than 30 years of editing and journalism experience to the CardRates team. She has worked at The Atlanta Journal and Constitution, Gwinnett Daily News, Gainesville Sun, and The New York Times, where she covered demographics, consumer issues, and the business and financial sectors. Lillian has a degree in journalism and communications from Georgia State University and brings her fact-checking expertise to ensure Digital Brands content is accurate and engaging.
Ashley Fricker has more than a decade of experience as a finance contributor and editor, and has specialized in the credit card industry since 2015. Her credit card commentary is featured on national media outlets that include CNBC, MarketWatch, Investopedia, and Reader's Digest, among many others. She has worked closely with the world’s largest banks and financial institutions, up-and-coming fintech companies, and press and news outlets to curate comprehensive content and media. Ashley holds a bachelor's degree in multimedia journalism from Florida Atlantic University.
Disclosure: When you apply through links on our site, we may earn a referral fee from our partners. For more, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation from many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across the site (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Many consumers think they know how to use a credit card (swipe and go, right?) — and while that covers the basics — it’s well worth taking a closer look at rewards, strategies, and the different types of cards available.
Credit cards are the most popular way to shop online and in-store, and it’s no wonder why. With the ability to securely shop at almost every location nationwide, plastic is quickly replacing cash and checks as a method of payment. While some stores have restrictions on the brand of card accepted, most are open to taking Visa, MasterCard, Discover, and American Express.
Many stores are moving to the chip-and-PIN technology needed to process those fancy cards with the little square on the front (chip cards.) These cards are inserted into a slot at the bottom of a card reader, instead of being swiped as we’ve been used to doing for the past decade or so, and are more secure than the magnetic strip cards of years past. Most cards have additional protections in place, outside of the retailer, to keep your information safe and your purchases legitimate. These same features are what keep your finances safe when buying online.
So, how do you know which card is right for you? And how can you get maximum benefits from your choice? Wise credit card use is key, so we’ve put together these tips to help. We’ll cover how to find the right card for your credit score, how to use credit cards responsibly, how to take advantage of rewards and other perks, and how to avoid those interest charges that can add up so quickly.
1. Get a Card for Your Credit Type
In a perfect world, everyone would qualify for the lowest interest rates and best perks a credit card has to offer. In real life, however, banks understand that not everyone has the same degree of risk, and that’s why they’ve developed card offers that are specific to an applicant’s creditworthiness and financial needs.
What is good for one person may be a terrible option for another. Pick the tier that best represents your credit profile below, then work to move up in rank for bigger and better card options!
If you’ve reached a FICO score at this level, you are considered a good credit risk and have the option to apply for some of these top-notch card offers. The following cards are designed to reward good financial decisions and provide cardholders with flexibility and competitive features.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $150 cash back into $300.
Earn 5% cash back on everyday purchases at different places you shop each quarter like grocery stores, restaurants, gas stations, and more, up to the quarterly maximum when you activate. Plus, earn unlimited 1% cash back on all other purchases.
Redeem cash back for any amount. No annual fee.
0% intro APR on purchases and balance transfers for 15 months; 17.49% - 26.49% variable APR after that; balance transfer fee applies.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Earn $200 cash back after you spend $1,500 on purchases in the first 6 months of account opening. This bonus offer will be fulfilled as 20,000 ThankYou® Points, which can be redeemed for $200 cash back.
Earn 2% on every purchase with unlimited 1% cash back when you buy, plus an additional 1% as you pay for those purchases. To earn cash back, pay at least the minimum due on time. Plus, earn 5% total cash back on hotel, car rentals and attractions booked with Citi Travel.
Balance Transfer Only Offer: 0% intro APR on Balance Transfers for 18 months. After that, the variable APR will be 18.49% - 28.74%, based on your creditworthiness.
Balance Transfers do not earn cash back. Intro APR does not apply to purchases.
If you transfer a balance, interest will be charged on your purchases unless you pay your entire balance (including balance transfers) by the due date each month.
There is an intro balance transfer fee of 3% of each transfer (minimum $5) completed within the first 4 months of account opening. After that, your fee will be 5% of each transfer (minimum $5).
Intro (Purchases)N/A
Intro (Transfers)0% 18 months on Balance Transfers
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Earn a one-time $200 cash bonus after you spend $500 on purchases within 3 months from account opening
Earn unlimited 1.5% cash back on every purchase, every day
$0 annual fee and no foreign transaction fees
Earn unlimited 5% cash back on hotels, vacation rentals and rental cars booked through Capital One Travel
No rotating categories or sign-ups needed to earn cash rewards; plus, cash back won't expire for the life of the account and there's no limit to how much you can earn
0% intro APR on purchases and balance transfers for 15 months; 18.49% - 28.49% variable APR after that; balance transfer fee applies
Perhaps you’ve made a few credit mistakes but are well on your way to a brighter financial future. You are considered to have fair credit and can still take advantage of a number of cards with more lenient application requirements. These cards are popular for those who are working hard to get closer to a credit score nearer the national average (695, for the year 2017.)
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
No annual or hidden fees. See if you're approved in seconds
Be automatically considered for a higher credit line in as little as 6 months
Help build your credit through responsible use of a card like this
Enjoy peace of mind with $0 Fraud Liability so that you won't be responsible for unauthorized charges
Monitor your credit score with CreditWise from Capital One. It's free for everyone
Get access to your account 24 hours a day, 7 days a week with online banking from your desktop or smartphone, with Capital One's mobile app
Check out quickly and securely with a contactless card, without touching a terminal or handing your card to a cashier. Just hover your card over a contactless reader, wait for the confirmation, and you're all set
Pay by check, online or at a local branch, all with no fee - and pick the monthly due date that works best for you
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Earn unlimited 3% cash back at grocery stores (excluding superstores like Walmart® and Target®), on dining, entertainment and popular streaming services, plus 1% on all other purchases
No rotating categories or limits to how much you can earn, and you can use your cash back for any amount–get gift cards, cover purchases or redeem for cash. Plus, rewards don’t expire for the life of the account
Be automatically considered for a higher credit line in as little as 6 months
Help strengthen your credit for the future with responsible card usage
Enjoy unlimited access to your credit score and tools to help you monitor your credit profile with CreditWise from Capital One
Enjoy peace of mind with $0 Fraud Liability so that you won't be responsible for unauthorized charges
Earn 8% cash back on Capital One Entertainment purchases with your SavorOne Card and enjoy exclusive access and cardholder perks
Earn unlimited 5% cash back on hotels, vacation rentals and rental cars booked through Capital One Travel
Capital One SavorOne cardholders can pay with their rewards via PayPal Pay with Rewards and at Amazon.com
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $50 cash back into $100. Or turn $100 cash back into $200.
Earn 5% cash back on everyday purchases at different places you shop each quarter like grocery stores, restaurants, gas stations, and more, up to the quarterly maximum when you activate. Plus, earn unlimited 1% cash back on all other purchases.
Redeem cash back for any amount.
No annual fee.
0% intro APR on purchases for 6 months, then the standard variable purchase APR of 16.49% - 25.49% applies.
If you’re just getting started with credit or working to move past a few mistakes, the good news is that many banks understand rebuilding takes time. These credit cards are built for people who are still paying off old debts or trying to re-establish credit after bankruptcy or a settlement. This list shows that a lower score doesn’t have to keep you from finding a dependable card account.
Matt Schulz of CreditCards.com shares that an unsecured card may also be an option for those with poor credit. “It works just like a regular credit card but keeps the risk to a minimum for everyone involved. Put $200 to get the card, put a few small purchases on it each month and then pay the balance in full. Do that repeatedly and before you know it, you’ll be ready to graduate to another card with better terms and better rewards.”
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
No annual or hidden fees. See if you're approved in seconds
Building your credit? Using the Capital One Platinum Secured card responsibly could help
Put down a refundable security deposit starting at $49 to get at least a $200 initial credit line
You could earn back your security deposit as a statement credit when you use your card responsibly, like making payments on time
Be automatically considered for a higher credit line in as little as 6 months with no additional deposit needed
Enjoy peace of mind with $0 Fraud Liability so that you won't be responsible for unauthorized charges
Monitor your credit score with CreditWise from Capital One. It's free for everyone
Get access to your account 24 hours a day, 7 days a week with online banking to access your account from your desktop or smartphone, with Capital One's mobile app
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
College students have unique borrowing needs. They may not have had any blemishes on their credit histories, but they also haven’t had enough history to appear reliable to lending institutions. While students work hard to build credit under their own names, these cards can offer many of the same protections and perks as those offered to more established consumers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $50 cash back into $100. Or turn $100 cash back into $200.
Earn 5% cash back on everyday purchases at different places you shop each quarter like grocery stores, restaurants, gas stations, and more, up to the quarterly maximum when you activate. Plus, earn unlimited 1% cash back on all other purchases.
Redeem cash back for any amount.
No annual fee.
0% intro APR on purchases for 6 months, then the standard variable purchase APR of 16.49% - 25.49% applies.
Capital One Quicksilver Student Cash Rewards Credit Card
4.6/5.0
About this rating
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
INTRO OFFER: Unlimited Cashback Match for all new cardmembers. Discover will automatically match all the cash back you’ve earned at the end of your first year! There’s no minimum spending or maximum rewards. You could turn $50 cash back into $100. Or turn $100 cash back into $200.
Earn 2% cash back at Gas Stations and Restaurants on up to $1,000 in combined purchases each quarter, automatically. You'll still earn unlimited 1% cash back on all other purchases.
Redeem cash back for any amount.
0% intro APR on purchases for 6 months, then the standard variable purchase APR of 16.49% - 25.49% applies.
While time generally heals all wounds (and will eventually move a bad mark off your credit history), a more effective way to build credit is to handle your debt responsibly. There are many ways to prove that you are a good credit risk and to push your FICO Score in the right direction:
Pay in advance of your due date; if possible, pay your bill in full every month.
Be aware of your credit limit, never charge more than you have available.
Watch your transaction history carefully; report suspicious activity right away.
Never lend out your card or card number to someone else.
If you have questions regarding your account, contact your card company.
A lot of credit trouble starts when cardholders can’t cover their minimum payment each month. Make sure you know what you owe, and do your best to pay at least the required amount on time. If something gets in the way, call your card issuer before the due date to explain your situation and ask about other payment options. Repeated late payments can lead to negative marks on your credit report, higher rates, and added fees.
3. Earn Rewards & Bonuses Through Qualifying Purchases
If you ask cardholders what they love most about their favorite card, they will probably reply with the “perks.” In fact, personal finance author Donna Freedman uses her rewards credit cards for everyday stuff like groceries, utilities, and medical co-pays. When she has earned enough points, she redeems them for gift cards that will later pay for her holiday and birthday shopping. Being wise with rewards cards helps free up money in her budget by taking care of 90% of the gifts she purchases each year!
The most common types of rewards and bonuses include:
Cash back: This is awarded as a percentage of qualifying purchases (1-5%, for example.) It is paid out at the end of the promotional period, quarterly, or when a certain threshold has been reached as either cash, check, or a statement credit. Some promotions or purchase types will pay more than the standard rate. Always sign up for bonus cash back offers your card may advertise throughout the year.
Airline miles: This type of reward currency can be used for flights, upgrades, hotels, rental cars, and more. Miles don’t have to be earned only through official airline cards, however. Many travel-friendly cards will give out generic “miles” that can then be transferred to the frequent flier program of your choice. Some will even allow you to “erase” past travel purchases by simply crediting your statement when you’ve earned a certain number of reward miles.
Points and gifts: Some cards use their own currency to hand out rewards. These can be done as a point system (which can be redeemed for a variety of merchandise awards, gift cards, or cash). Another option is a store credit card, which works with just one retailer or vendor to offer gift cards or credit to that company alone. They are most beneficial to customers who are fiercely brand loyal and want a card that rewards this fact.
Gas rewards: These types of rewards are self-explanatory. Earn rewards on your gas purchases, sometimes saving the most when you churn those reward points back into gas gift cards or credit at the pump.
Of course, your rewards can go further when you use signup bonuses to jump-start your earnings. Many cards will offer new applicants a large gift of points or gift cards to sweeten the deal. These are good opportunities to cash in with a card you wanted to sign up for anyway!
Remember, cards usually only award points, rewards, miles, or other perks for qualifying purchases. While this definition will vary from card to card, the general rule is that you only earn on purchases as defined by the terms of the promotional offer. Balance transfers and cash advances almost never count, and many qualifying purchases may be limited by the retailer, date processed, or the cardholder on the account. It’s wise to read your credit card documentation or contact a card rep if you are unsure whether a purchase qualifies for a special offer or reward perk.
4. Avoid Interest Charges by Paying Your Balance Off
Cards are a fantastic tool if used properly. They can help you build wealth and give you flexible ways to pay for purchases. But what happens if you don’t pay for all your shopping before your statement hits the mail?
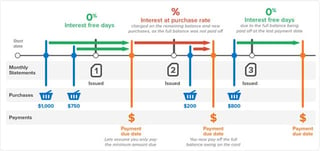
To be certain you don’t pay more than the original price of your purchase, know your grace period. This is the number of days you have from the time you charge something until you start paying interest. Make sure your purchases are paid for in full before this time runs out!
You’ll also want to be familiar with your interest rate, often called “APR.” This APR (annual percentage rate) is the amount of interest your credit card company will charge you – each year — for not paying your balance in full. This interest starts accruing the day your grace period ends.
Skip this drama entirely by paying your credit card bill in full each month. Bobby Lee of 2-Minute Finance advises beginner cardholders to reserve a card for large purchases only (say, $50 and up.) “At the end of the week, set aside money from your checking account to cover those purchases,” Bobby recommends.
These weekly “set-asides” will ensure that you’re not spending more than you have available to pay. In addition, the higher purchase amount threshold makes you pause and think before spending money. Never paying interest requires you to never fall into the trap of carrying a balance from month to month.
5. Enjoy the Perks & Protections of Owning a Credit Card
In addition to rewards, such as cash and travel miles, there are other card benefits that you would be wise to take advantage of. These include certain purchase protections and the ability to access a line of credit for unexpected large buys or emergency situations.
Bobby Lee’s favorite protection is hands down, the return protection that many cards offer. “If you want to return an item you bought online or in-store, but the retailer refuses to take it back, your credit card has you covered,” he explains.
He’ll usually use this coverage when a return falls outside the retailer’s return window but still fits within the credit card’s 90-day claim period. That’s a savvy move!
There are many perks to owning a credit card, especially if you use it to build your credit and get increasingly better card offers over time. It’s not a bad idea to regularly check your score, see where you fall in the tiered card system mentioned above, and re-apply every year or so for a better card than what you have. As you use credit wisely and climb the card ladder, you’ll get bigger and better perks and protections to make life easier and more rewarding.