
Writer: Jon McDonald


Editor: Adam West


Reviewer: Ashley Fricker

Key Takeaways
Whether it’s for unexpected vet costs or smaller ongoing costs, a dedicated pet credit card could help you save money. Here are the first two I’d recommend:
-
BankAmericard® credit card: Best for large bills with its 0% intro APR.
-
Capital One Savor Cash Rewards Credit Card: Best for cash back on pet supplies. See rates & fees
My 13-year-old dog has a chronic condition. It’s completely manageable, but requires regular trips to the vet (along with standard senior dog appointments). The bills for her care and medicines add up fast, but she’s part of the family.
For the average person, the cost of veterinary care can be prohibitive. Even with pet insurance, certain conditions, procedures, and supplies aren’t always covered in full (or at all).
But some credit cards, including specialized pet cards, offer rewards or even 0% intro APR, that can take some of the bite out of the high cost of pet supplies or vet bills. Here, I’ll share some of the best I’ve found.
Best for 0% Intro APR: BankAmericard® credit card
I could take my time repaying a large vet bill if I put it on a new BankAmericard® credit card. That’s because I would have 0% Intro APR for 21 billing cycles for purchases, giving me a long runway to pay off the balance.

- 0% Intro APR for 21 billing cycles for purchases, and for any balance transfers made in the first 60 days. After the Intro APR offer ends, a Variable APR that’s currently 15.24% – 26.24% will apply. A 5% fee applies to all balance transfers. Balance transfers may not be used to pay any account provided by Bank of America.
- No annual fee.
- No penalty APR. Paying late won’t automatically raise your interest rate (APR). Other account pricing and terms apply.
- This offer may not be available elsewhere if you leave this page. You can take advantage of this offer when you apply now.
Additional Disclosure: Bank of America is a CardRates advertiser.
After the intro 0% APR period ends, its 15.24% - 26.24% Variable APR on purchases and balance transfers kicks in. Given this, clearing the balance before interest fees start is a must.
Personally, I’d divide the vet bill into 19 equal payments, giving myself a two-month buffer because, well, life. Then, I could treat it as a fixed monthly expense and breathe easier because I’d be taking full advantage of the promotional rate.
Best for Everyday Supplies: Capital One Savor Cash Rewards Credit Card
I buy a lot of pet food, treats, and supplies on my weekly trip to the grocery store. That’s why I’d consider the Capital One Savor Cash Rewards Credit Card. In addition to an intro APR offer of 0% for 12 months, I’d score serious cash back in many categories.
- Earn a one-time $200 cash bonus once you spend $500 on purchases within the first 3 months from account opening
- $0 annual fee and no foreign transaction fees
- Earn unlimited 3% cash back at grocery stores (excluding superstores like Walmart® and Target®), on dining, entertainment and popular streaming services, plus 1% on all other purchases
- Earn 8% cash back on Capital One Entertainment purchases
- Earn unlimited 5% cash back on hotels, vacation rentals and rental cars booked through Capital One Travel
- No rotating categories or sign-ups needed to earn cash rewards; plus cash back won’t expire for the life of the account and there’s no limit to how much you can earn
- 0% intro APR on purchases and balance transfers for 12 months; 18.74% – 28.74% variable APR after that; balance transfer fee applies
- Top rated mobile app
For example, I’d get 3% cash back at grocery stores (as well as on dining, entertainment, and popular streaming services), but just 1% cash back at big-box pet stores. Therefore, my regular pet purchases at the grocery store would put significantly more money back in my wallet.
This cash back card could be ideal for recurring costs and even high vet bills during its intro 0% APR window. Just know that once that promotional period ends, it reverts to the regular APR. So, I’d focus on paying off any remaining balance before that ends.
Best for Cash Back: Citi Double Cash® Card
Get cash back on large vet bills with the Citi Double Cash® Card. Do note, this card currently doesn’t have a 0% introductory period on purchases, so I’d try to pay the balance in full during the first billing cycle.
- Earn $200 cash back after you spend $1,500 on purchases in the first 6 months of account opening. This bonus offer will be fulfilled as 20,000 ThankYou® Points, which can be redeemed for $200 cash back.
- Earn 2% on every purchase with unlimited 1% cash back when you buy, plus an additional 1% as you pay for those purchases. To earn cash back, pay at least the minimum due on time. Plus, earn 5% total cash back on hotel, car rentals and attractions booked with Citi Travel.
- Balance Transfer Only Offer: 0% intro APR on Balance Transfers for 18 months. After that, the variable APR will be 18.49% – 28.74%, based on your creditworthiness.
- Balance Transfers do not earn cash back. Intro APR does not apply to purchases.
- If you transfer a balance, interest will be charged on your purchases unless you pay your entire balance (including balance transfers) by the due date each month.
- There is an intro balance transfer fee of 3% of each transfer (minimum $5) completed within the first 4 months of account opening. After that, your fee will be 5% of each transfer (minimum $5).
Additional Disclosure: Citi is a CardRates advertiser.
Cash back is an unlimited 2% across categories, but the way it’s distributed is a little different. I’d get 1% cash back on every purchase and an additional 1% cash back when I pay off that purchase on my monthly bill. And there’s no limit to how much cash back I could earn.
The flat-rate cash back model makes it ideal for follow-up vet visits, medication refills, and grooming appointments across merchants. This could save me the hassle of trying to remember which card offers a higher percentage of cash back at different types of retailers.
3 Dedicated Pet Credit Cards
While general credit cards are much more useful in everyday life, there are a handful of cards designed for pet purchases. Those purchases may include supplies, grooming, or vet care.
But cards in this category can be much more restrictive and potentially costly, so don’t expect a lot of flexibility.
Petco Pay Mastercard®
If I only shopped at Petco for pet supplies, I’d consider the Petco Pay Mastercard®. That’s because I’d get 10 extra Petco Perks for every dollar spent on pet food, grooming, and supplies (both in-store and online).
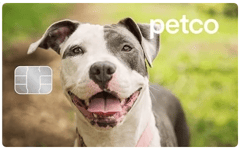
- Earns an effective 6% back in rewards on Petco purchases with no annual fee.
- Extends reward expiration to one year and gives 20% off your first Petco purchase.
- Includes deferred-interest financing on transactions of $299 or more.
But just know the rewards are also locked in to Petco, as every 1,000 points equates to $1 in Petco Cash. Another cool feature is that I can put a picture of my pet on the credit card.
The Petco Pay Mastercard® also offers deferred interest financing options with lengths of 6, 9, or 12 months for purchases starting at $299. And pay off the balance before the promotional period ends is critical. If there’s any left over, an APR that could go higher than 34% would be charged for the entire amount.
This card wouldn’t be ideal if I bought pet food or supplies (or got my pup groomed) anywhere else, though. But die-hard Petco loyalists could see plenty of savings with this card.
All Pet Credit Card
The All Pet Credit Card is strictly limited to pet expenses, and it can be used for routine and emergency pet care, boarding, daycare, grooming, and prescription medications.
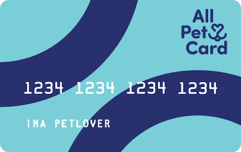
- Accepted exclusively at participating veterinary clinics and pet care facilities.
- Provides a 6-month deferred-interest financing plan for purchases exceeding $250.
- Applies a steep retroactive APR if the balance isn’t paid entirely within the promotional window.
As a pet parent, having this card in my wallet would reduce my anxiety. Knowing I’m able to provide my pet with emergency care if they have an accident or get sick can provide a peace of mind that’s priceless.
But this card does have some fine print that would give me pause. It offers six months of deferred interest on all purchases over $250, but if I don’t pay off the entire balance within that time frame, the regular 32.99% APR would apply to the entire bill, not just the remaining balance.
CareCredit Credit Card
The CareCredit credit card is another card designed to finance health and wellness expenses. It offers deferred interest (i.e., a 0% interest promotional period) terms of six, 12, 18, and 24 months, which allows me to make installment payments.
- Widely accepted at a variety of veterinary locations for pet medical expenses.
- Offers flexible deferred-interest promotional periods ranging from 6 to 24 months.
- Charges a high retroactive APR on the original principal if the strict timeline is missed.
That could help me stretch out a big vet bill, but I’d need to be very careful. If I don’t pay off the entire bill by the end of the deferred interest period, that interest will come back in a big way.
That’s because I’ll be charged retroactive interest accrued during the introductory period, which is currently 32.99% APR for new accounts.
Credit Card Acceptance, Surcharges, and What to Ask the Vet
Vets often impose a credit card processing fee, typically 2.5% to 3.5%, to offset processing costs charged by credit card issuers. So, if the cost of care was $500, a 3% processing fee would add an additional $15 to my bill.
Since the cost of care (especially large, unexpected bills) can be exorbitant, many vets offer in-house or third-party payment plans. This could allow me to make installment payments, instead of having to pay the balance in full when the service is rendered.
That’s why I’d ask the following questions before getting care to avoid getting hit with surprise fees:
- Can I have an itemized list of all charges?’
- Is there a credit card surcharge? If so, what percentage?
- Is there a discount for paying with cash or debit card?
- For an in-house payment plan, ask about the repayment schedule, administrative fees, interest charges, late fees, and any potential down payment costs
Of course, if I planned to pay with a credit card that has a 0% introductory APR window (and also planned to pay in full before the promotional period ends), I could avoid a lot of these concerns. Except the credit card surcharge; that one is likely unavoidable.
Frequently Asked Questions
What Exactly Is a Pet Credit Card?
On the surface, a pet credit card might sound like a general bank card, but it’s not. A veterinary medical card or a pet store card tends to have limited use. For example, I may only be able to use the card for a specific purpose (like vet care) or earn rewards at a specific store.
Conversely, a general bank card can be used anywhere. There aren’t the same limitations on the types of products or services I can purchase, as long as the retailer accepts my card.
A credit card offering mainstream rewards and/or a 0% intro APR is typically the better choice. The expanded selection of rewards increases ease of use, and a 0% introductory APR allows me to make installment payments during the promotional period without incurring extra fees.
How Does a 0% Intro APR Card Help Pay a Vet Bill?
Paying for veterinary care can be a challenge, especially in an emergency. A 0% intro APR card can be a game-changer because it gives me the chance to make installment payments without incurring interest.
However, ensuring the balance is paid in full before the introductory period ends is key. If I fail to do so, I’ll have to pay interest on the remaining balance.
I’d suggest creating a payoff plan immediately so I don’t run up against the end of that interest-free window. Dividing the balance by the number of months covered by the promotional plan is the easiest route.
For example, if I owe $1,000 on a card with a 12-month deferred interest period, I’ll need to pay about $83.33, at minimum, every month for a year. Personally, I like to subtract a couple of months before I divide the balance to give myself a buffer in case anything happens.
What Should I Do If My Vet Doesn't Accept My Credit Card?
The only thing worse than incurring a large vet bill is not being able to pay it. I avoid this by asking for an itemized estimate upfront, so I know exactly what I’m getting into.
However, if the vet doesn’t accept your card, ask whether in-house or third-party financing is available. You may be able to work out a payment plan that fits your budget (and doesn’t max out your credit card).
If this isn’t an option, I’d ask if my vet offers delayed billing. I’d still have to pay the bill, but I may be able to wait until my next paycheck.
It’s also possible the vet offers a cash discount. And even a slight cost reduction could make a big difference.
Are Pet Credit Cards Worth It?
Pets are part of the family, so providing them with the care they need is a must. Given this, I’d say having a credit card that can handle your pet expenses is definitely worth it.
Cash back credit cards can provide a steady stream of benefits on the things I already buy.
If my pet needs care I can’t pay for in full immediately, a 0% introductory APR card could provide financial support and some breathing room. Assuming I settle the balance before the promotion ends, I can avoid paying a dime in interest.
The Right Credit Card Can Help Your Pet Stay Happy & Healthy
Having a credit card to deal with pet expenses is worth it, but not all options are equal. Choosing the right credit card is vital to your financial health (which can obviously impact your pet’s health).
I’d recommend a 0% intro APR card as the best choice for big vet bills because it offers the option to make payments over time without incurring interest. But just know that interest will be charged on the entire balance if any remains after that window closes.
As for everyday pet staples, I’d recommend a cash back card. When possible, try to buy the bulk of your pet supplies at the type of store that offers the highest percentage of cash back for that specific card.
Waiting until a pet emergency to plan how to finance care could lead to a costly decision. But deciding on the approach now can ensure you have a solid plan if your pet ever needs it.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author