My Comprehensive Review of the BankAmericard® credit card: A Card for Those Who Don’t Like Interest
This card's long 0% APR runway could really help your finances take off.
By: Erica Sandberg
Erica Sandberg, Finance Expert
Erica Sandberg is a consumer finance expert and journalist whose articles and insights are featured in publications such as the Wall Street Journal, Reuters, MarketWatch, Forbes, and MSN Money.
An experienced media host, she's led many financial programs, including her podcast, "Adventures With Money." She's appeared on Fox, CNN, "EconTalk" and "The Dr. Drew Podcast," and has been the resident money and credit authority for KRON-4 News in San Francisco for more than 10 years.
She's also the author of "Expecting Money: The Essential Financial Plan for New and Growing Families" and recipient of the 2024 Financial Literacy and Education in Communities (FLEC) Award for National Excellence.
Jon leverages 15-plus years of journalism expertise to inform financial consumers about emerging trends and companies making an impact in the industry. He is most knowledgeable in the areas of budgeting, credit card rewards, and responsible credit use. Jon has a passion for writing and editing, and his articles have appeared in publications produced by The New York Times.
Ashley Fricker has more than a decade of experience as a finance contributor and editor, and has specialized in the credit card industry since 2015. Her credit card commentary is featured on national media outlets that include CNBC, MarketWatch, Investopedia, and Reader's Digest, among many others. She has worked closely with the world’s largest banks and financial institutions, up-and-coming fintech companies, and press and news outlets to curate comprehensive content and media. Ashley holds a bachelor's degree in multimedia journalism from Florida Atlantic University.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
As a credit counselor, I worked with countless people who had debilitating credit card debt. I’ll never forget one woman who desperately wanted to pay off her credit card balances. She was sending the minimum payments on time, but her debt barely budged, and she wanted to know why.
After an hour of explaining and showing how most of her payment was going toward financing fees rather than the principal, she suddenly looked up. “Ah, so that’s how they getcha!” she said.
Sure, added interest is a problem, but there is also a solution. Outside of paying your monthly bill in full, you can get an account that doesn’t charge any interest for a long while, such as Bank of America’s BankAmericard® credit card.
Watch on
I would absolutely recommend it to anyone who qualifies and wants the luxury of 21 months of interest-free debt.
You can find out if you’re eligible by going through the simple prequalification process, too, which will protect your credit against unnecessary hard credit inquiries.
The extra-long 0% APR deal takes the place of a rewards program. Therefore, if what you’re most interested in is a way to borrow money for purchases or transfer a high balance without financing fees adding up, the BankAmericard® credit card may be your lightbulb moment.
What to Expect With the BankAmericard® credit card
Now, there are plenty of credit cards that offer 0% APR on purchases and balance transfers, but the typical time frame is considerably less. The most common durations are 12, 15, and 18 months.
Disclosure: When you apply through links on our site, we often earn referral fees from partners. For more information, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation for referrals for many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across CardRates.com (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
0% Intro APR for 21 billing cycles for purchases, and for any balance transfers made in the first 60 days. After the Intro APR offer ends, a Variable APR that’s currently 15.24% – 26.24% will apply. A 5% fee applies to all balance transfers. Balance transfers may not be used to pay any account provided by Bank of America.
No annual fee.
No penalty APR. Paying late won’t automatically raise your interest rate (APR). Other account pricing and terms apply.
This offer may not be available elsewhere if you leave this page. You can take advantage of this offer when you apply now.
Intro (Purchases)0% Intro APR for 21 billing cycles for purchases
Intro (Transfers)0% Intro APR for 21 billing cycles for any balance transfers made in the first 60 days (Balance Transfer Fee 5% of the amount of each transaction)
Regular APR15.24% – 26.24% Variable APR on purchases and balance transfers
Annual Fee$0
Credit NeededExcellent/Good
Additional Disclosure: Bank of America is a CardRates advertiser.
Since the BankAmericard® credit card offers 21 months, it’s on the high end of the spectrum. Because of this, it is really designed for people who are most interested in initially charging large sums or transferring high balances without worrying about the interest that makes revolving debt so expensive.
No Annual Fee
I have a few credit cards, one of which has an annual fee. It’s a good card, so I’m keeping it, but every year on my account anniversary, I need to prepare for the $95 that hits my bill.
Since the BankAmericard® credit card has no annual fee, you won’t have to concern yourself with that. What you will have to do, though, is determine whether or not you want to keep the card after the 0% APR period is over.
Hanging on to the card and using it regularly will keep your credit history with that account going, which can be good for your credit rating. Because it has no annual fee, it won’t hurt to keep it open, even though you won’t get the zero-interest deal again.
Penalty APR Safety Net
I’m accustomed to warning people about problems associated with missing a payment. That great 0% APR deal you had can suddenly be ripped away from you if you’re even a day late. And the entire balance you transferred may be subject to the card’s regular rate.
Not so with the BankAmericard® credit card. Your 0% intro rate will stay put for the entire 21 billing cycles. This is a highly unusual safety net, and it can provide valuable peace of mind as you’re paying off debt.
That doesn’t mean you won’t face some repercussions, though. If you pay late, you may be hit with a penalty fee of up to $41. That can be a big ouch.
And, of course, if you fall behind by an entire billing cycle, Bank of America will report you as delinquent, and your credit history and scores will be negatively affected.
Foreign Transaction Fee
Different credit cards serve different purposes. Those designed for travel rarely impose foreign transaction fees, so if you will be making international purchases, that’s the plastic you want to pack.
Although you can use your BankAmericard® credit card anywhere you are in the world, if you charge outside the U.S., a fee of 3% of the transaction amount will be applied.
For example, if you spend $5,000 while traipsing in Europe, the foreign transaction fee will be $150. Therefore, I wouldn’t bring it abroad as your primary card, but as a backup.
Introductory Offers & Other Benefits
Each credit card has its own flavor, and the deliciousness of the BankAmericard® credit card is its unusually expansive introductory financing package.
Instead of a rewards program where you earn cash back or points as you charge, you get 0% APR for 21 billing cycles. It can be an enormous financial benefit, and here’s why.
Imagine you have a credit card offering 2% cash back on everything you purchase. Spend $8,000 a year, and you will earn $160. That’s great! However, if you maintained the $8,000 balance and the card has a 22% APR, the accumulated interest would be $1,968. Not great at all.
But if you opened the BankAmericard® credit card, you would have 21 months to pay it off with no added interest. Instead of cash back or points, not being charged financing fees is the reward. If you transfer a balance, all it will cost you is the transfer fee.
0% APR Offer For Purchases and Balance Transfers
If you open this card, you can use it to make purchases for the things you want and need, but you don’t have to pay the bill in full by the due date to avoid interest. At least not for 21 billing cycles, that is.
This feature makes the BankAmericard® credit card ideal for planned purchases that you want to pay over time. Say a room of new furniture costs around $6,000. As long as you send $300 per month (or in varying increments, as long as the debt is repaid in full by the 21st billing cycle), no interest will be added.
And then there are balance transfers. This card gives you the option to shift just about any non-Bank of America debt to your BankAmericard® credit card, including balances on other credit cards and a wide variety of loans (personal, student, car, and even home equity).
Of course, the balance transfer amount has to fall below your credit limit. But know that if you do use up most of your credit line, it can negatively impact your credit score until it’s well below that line.
That’s because it will affect your credit utilization, or the amount of credit you use compared to your total credit limit. This is the second most important factor in FICO scores, behind payment history.
Also, make sure that you take swift action, since you have to make your balance transfer within the first 60 days of opening the account. If you do wait two months, that will also shave time off your interest-free payment window.
A 5% fee will be added to the balance, too, so if you transfer $10,000, prepare for a balance transfer fee of $500.
Account Security and Protection Perks
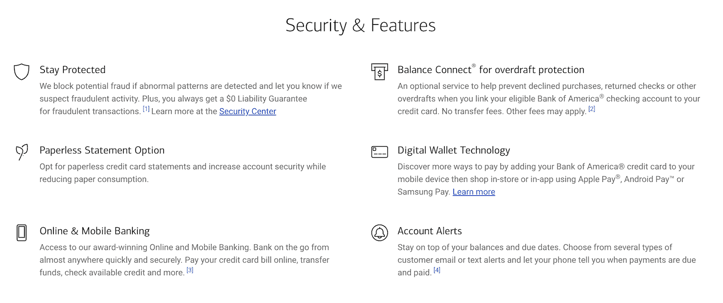
Just because the BankAmericard® credit card is relatively basic doesn’t mean it’s without a healthy level of security and protection.
First, it comes with a $0 liability guarantee. This means you will not be held responsible for any transactions you did not make or authorize.
If someone does use your card without your permission, report that activity within 60 days of your statement date. Lock your card (which you can do on the app, website, or over the phone) and submit a dispute for the charges.
Bank of America also takes steps to monitor card activity and check for abnormalities. If it finds anything suspicious, the bank will block the transaction and notify you.
Bank of America security features at a glance.
The BankAmericard® credit card is equipped with contactless payment technology, so you can use it at any terminal that accepts tap-to-pay. The tap-to-pay feature generates a unique security code, which protects your account numbers from being shared.
You can add this account to such digital wallets as Apple Pay, Google Pay/Wallet, and Samsung Pay/Wallet, so you can leave your actual card at home and make purchases while you’re out and about.
It’s a safe process because your account number isn’t stored on the device. Instead, a secure, digital substitute number will process those transactions. You can also integrate it with Paze, so you can buy things online as well as at many retailers and restaurants.
Mobile App Features & Support Tools
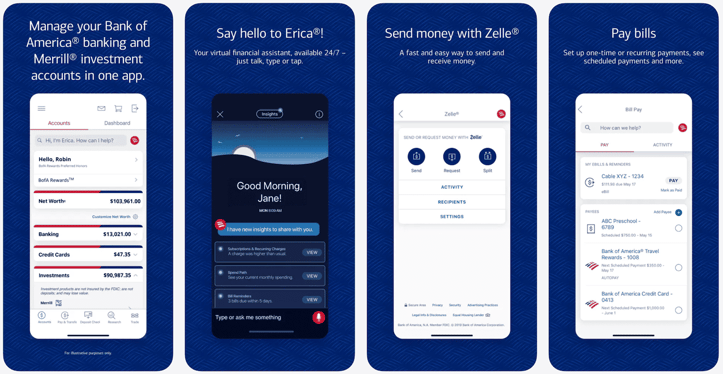
I’ve been using Bank of America’s mobile app since it was introduced in 2007, and what I most appreciate about it is how easy it is to navigate. I can’t stand “messy” apps where I can never find anything. This app defines user-friendly.
If you’re like me, you’ll use it to review your most recent balances and transactions, but it also includes several tools you may use from time to time. For example, with My Credit, you can view your FICO score and credit report, allowing you to keep track of how you are doing with your overall creditworthiness.
The Bank of America mobile app is easy to use and has lots of valuable features.
You can also use the app to set account alerts, which give you immediate information about payments, debt levels, scoring changes, and when you reach certain goals.
Don’t want to get monthly paper statements anymore? No problem. Just sign up for digital statements, and they’ll come to you electronically.
FICO® Score Monitoring
There are some surprises that are great. A friend bringing you a big box of chocolates out of the blue, for example. But your credit score? That shouldn’t be a mystery.
Maybe you want to buy a car, but when you go to the dealership, you find out that your score isn’t where it should be to get the best rate. That can put you in a tough position, either being denied or being offered unattractive terms.
This is where the free My Credit tool shines even brighter.
With My Credit, you can view your TransUnion credit report, the most recent FICO score that’s based on your TransUnion report, and learn what may affect your score.
If you want to get pinged when your numbers increase or decrease, when you hit your credit score goal, or know when suspicious activity is occurring on your credit profile, ask Erica (not me; Bank of America’s AI assistant Erica®!) to pull up that information.
Balance Connect® Overdraft Protection
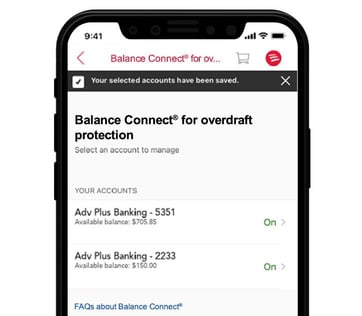
Ever spend too much and then exceed your checking account limit? You may appreciate Balance Connect, overdraft protection you can manage from the app or online.
To start, you can enroll your checking account and link up to five backup accounts, one of which might be the BankAmericard® credit card. If you don’t have enough cash in your checking account, Bank of America will automatically move funds from a backup account into your checking account, allowing the transaction to go through.
The BankAmericard can be a safety net for your checking account with Balance Connect.
Just know that overdraft transfers are processed as a credit card cash advance and have associated costs. Interest will be applied, and it starts immediately with no grace period.
The APR on a cash advance can also be higher than the APR for regular purchases. And this is very important: if you take out the BankAmericard® credit card because it offers the 0% APR introductory deal, you should know that cash advances are not covered by that offer.
Customer Support Channels & Responsiveness
I’m pretty sure the Bank of America customer service representatives know me by now! I don’t call unnecessarily, but when I have questions, I tend to pick up the phone. Besides, there are times when checking the app isn’t convenient.
For credit card customer service, call 1 (800) 732-9194, and for billing questions, you can call 1 (866) 266-0212. To test it out, I called customer service to find out exactly when a Zelle payment was credited to my account.
Yes, I could have gone to the app or checked online, but it’s nice to know that a representative was able to answer the question quickly, too. I just went through a series of prompts and was on hold for approximately four minutes.
As for my namesake, Erica®: This virtual assistant can do quite a number of things. Maybe you want to search for a specific transaction or track a refund. Simply ask, and you’ll find out.
If you want to know how much you spent at restaurants (or anywhere else) in a specific time period, you can do that, too.
But there are also limitations. If your question is complicated and personal, such as “Would it be better to pay down my credit card debt or my mortgage?” Erica won’t be able to answer. Nor can the virtual assistant help you do things like resolve fraud disputes or increase credit limits.
Requirements to Qualify
The BankAmericard® credit card is not designed for credit newbies or people with bad credit. Your credit scores should be in the good to excellent range. Think FICO scores of 670 and above.
Naturally, you will need to prove that you can afford to make your payments. That means available income, but other factors will also be considered.
How much you are paying for housing and current debt loads (such as other credit cards and loans) will all be assessed. You will want to be perceived as a very low-risk borrower.
Therefore, if you have a high credit score, a steady and good income, and low expenses and debt, you may be in a good position to qualify.
How to Apply (A Look at Every Step)
Before going through the actual steps to apply for this card, I see on the website that I can complete a prequalification form. When I start the prequalification process, I see all the details about the BankAmericard® credit card.
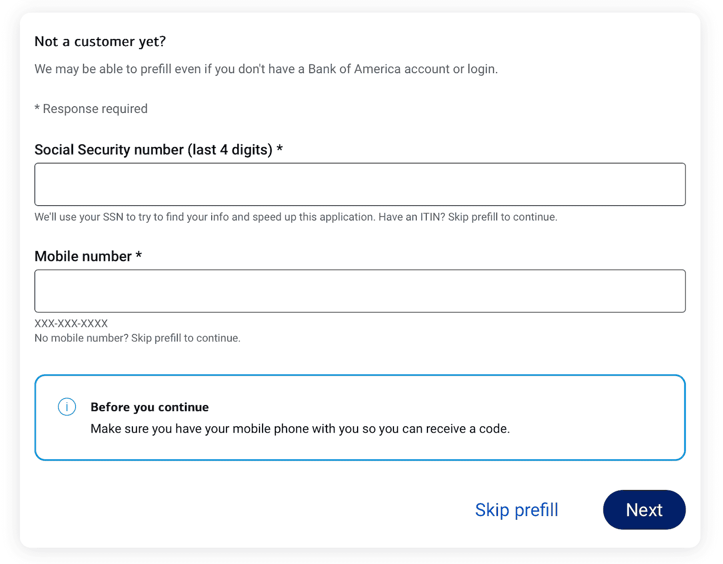
If I already have a Bank of America account, I can have it pre-filled with my information. Otherwise, I would fill out the form below, asking me to list the last four digits of my Social Security number and my mobile phone number.
I choose to go straight to the application by clicking on the blue “Apply Now” button.
Step 1: Mobile Number and Last Four Digits of Your SSN
Here I see verbiage about being able to save money on interest with this card’s low intro APR offer and no annual fee. I can also click on the terms and conditions to see exactly what this card entails.
Bank of America indicates that it will scour the information it already has about me if I am a current customer, and then will pre-fill my application.
I must enter the last four digits of my Social Security number and my mobile number in the fields. There is also a note saying I will need to have my mobile phone with me to receive a code.
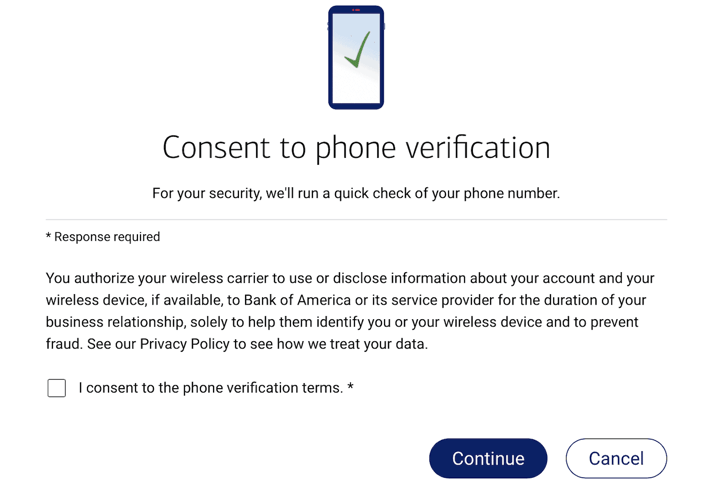
Step 2: Text Verification
Now I see a screen that shows I will be consenting to phone verification.
I check the box, then the blue “Continue” button.
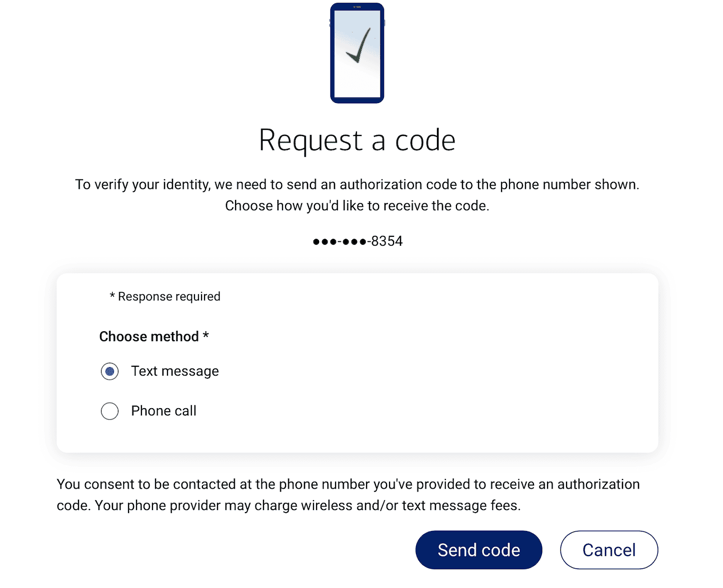
I am now invited to request a code that will come either via text message or a phone call by clicking the corresponding option.
I select “Text Message” and enter the authorization code that was sent to my phone.
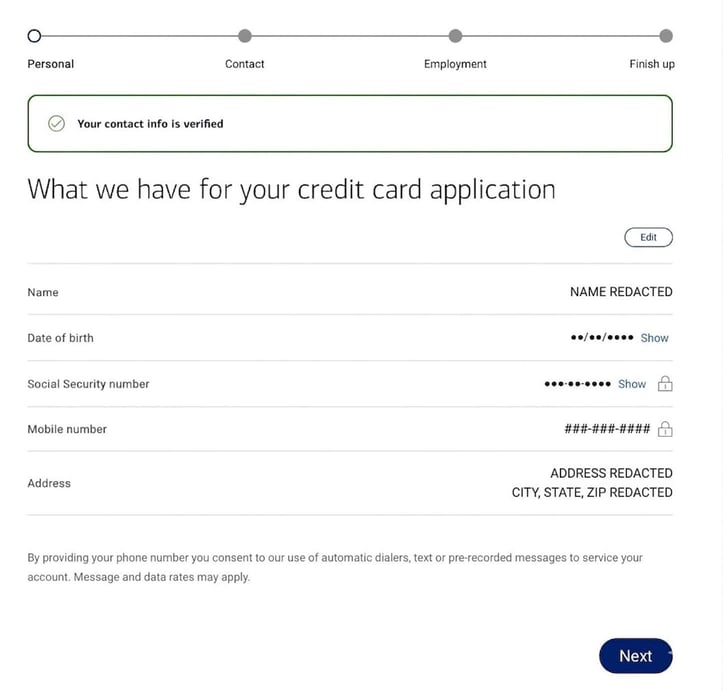
Step 3: Date of Birth, Full SSN, and Address
This brings me to a screen that has verified my existing information. Because I already have a Bank of America account, the data was filled in.
If I were not a Bank of America customer, I would have to fill in my date of birth, complete my Social Security number, phone number, and address.
I click on the blue “Next” button to move on to the next screen.
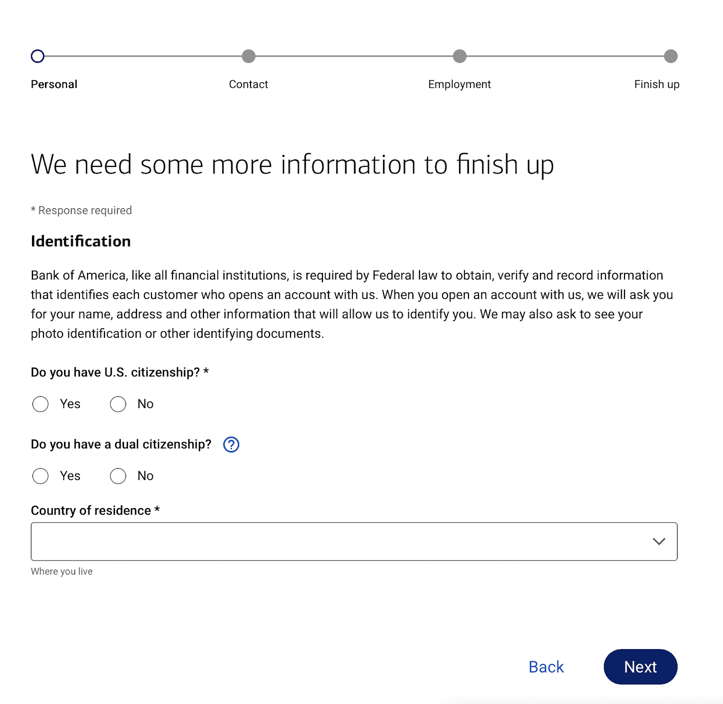
Step 4: Citizenship Status
Here I see that Bank of America needs some more information about my identity to finish up.
The form asks whether I have U.S. citizenship, and I can check either “Yes” or “No”. If I have dual citizenship, I can also note that.
Then, in a drop-down menu, I will choose from a long list of countries as my country of residence.
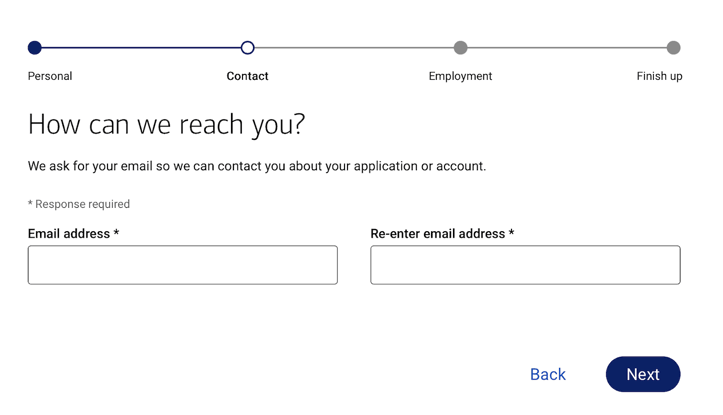
Step 5: Email Address
Now I come to a screen asking about how the bank can reach me. I am to supply my email address, and then re-enter it.
I do, and then click the blue “Next” button.
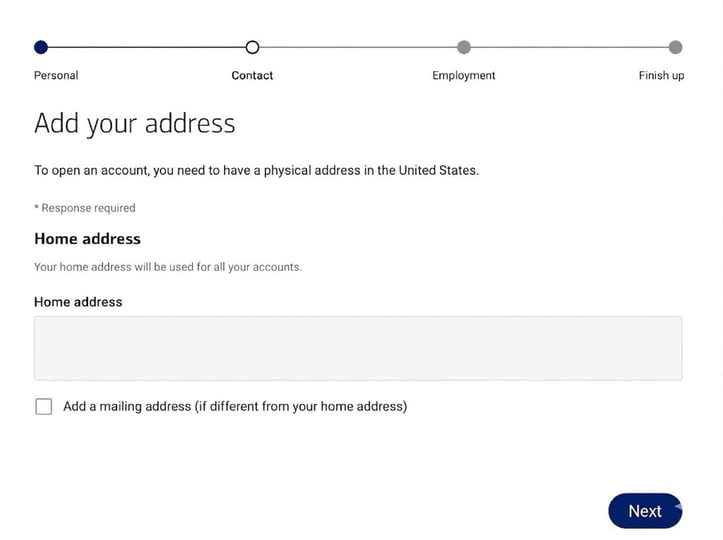
Step 6: Residential Address
I now come to a screen asking me to add my home address.
I see that in order to open an account, my physical address needs to be in the United States. If it is not already pre-included from other accounts, I would include it in the field here.
I click the blue “Next” button.
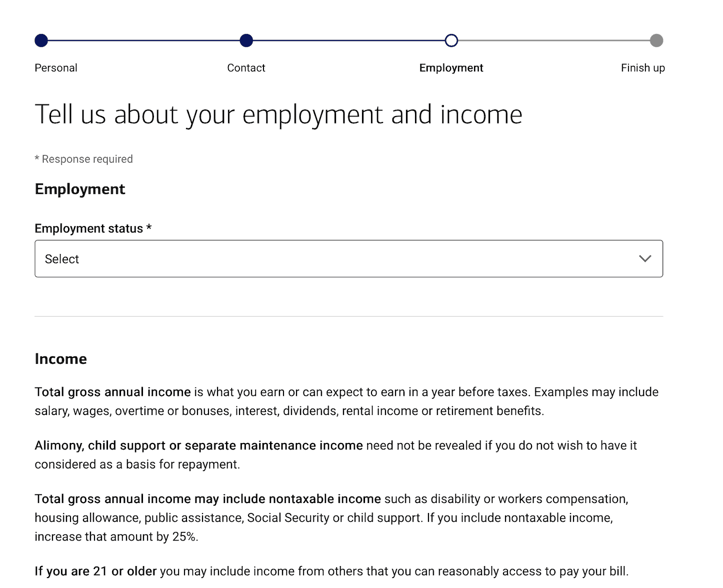
Step 7: Employment and Income
I now arrive at a screen asking about my employment and income.
For employment, I am to select from a drop-down menu. I can choose between employed, self-employed, retired, student-employed, student-unemployed, and unemployed.
If I’m employed in any way, another drop-down menu appears, where I am to select from a huge array of different occupations, from “senior political figure” to “writer.”
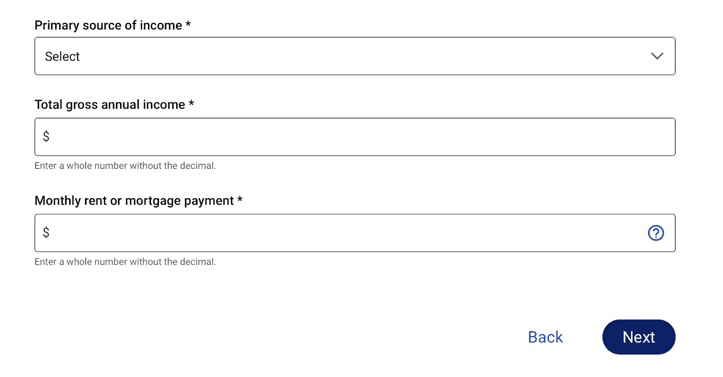
Another drop-down menu invites me to identify my primary source of income, which includes employment, inheritance/trust, investment, and Social Security.
Then I arrive at two additional fields. For one, I enter my total gross income, and for the other, I list my monthly rent or mortgage payment.
I complete both and move on to the next screen.
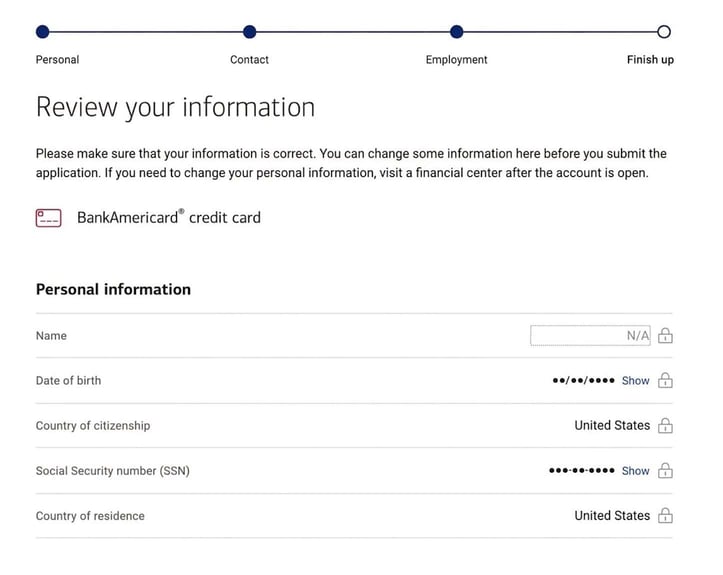
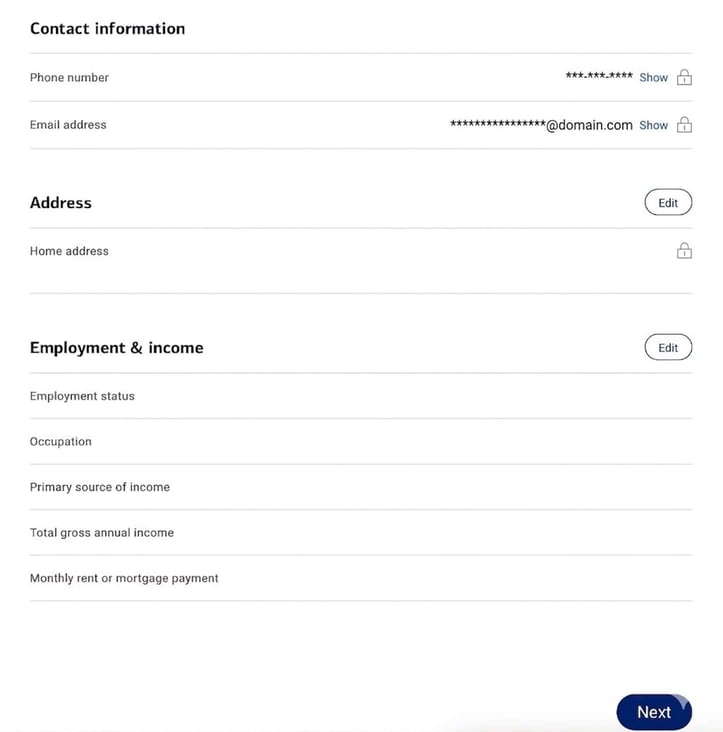
Step 8: Review Your Information
Now I can see all the data I have submitted. I am asked to review everything to make sure it’s all correct.
I can edit any information on this screen before submitting my application.
Everything looks right, so I continue on.
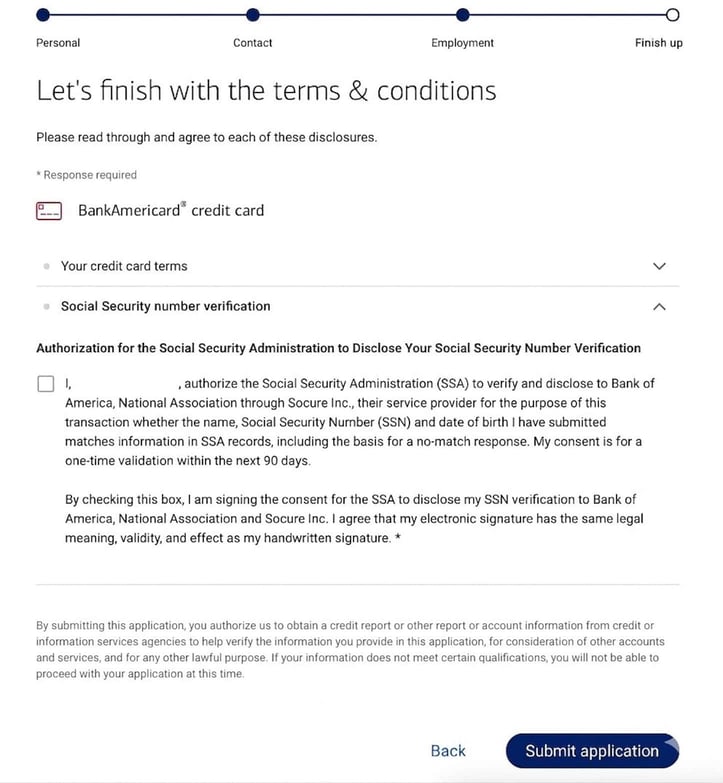
Step 9: Read Terms and Conditions and Submit Application
Here I see that I have come to the end of the application. This screen begins with a message about the terms and conditions of this card. I am to review all of the information.
A square box is underneath the terms and conditions, explaining that by submitting my application, I acknowledge that I have read and agree to them.
A Social Security number verification section is next. When I click the box, I see that I am signing the consent form and agree that my electronic signature is the same as my handwritten signature.
At the bottom of the page, I see a blue button with “Submit application.” If I click it (which I don’t), I will find out if I am approved.
What Credit Limit to Expect
Depending on your credit history, income, and other debt obligations, the credit limit for the BankAmericard® credit card can range from $1,000 to $20,000. To start, $3,000 is a common figure.
Pay close attention to this initial credit limit, though. If you do plan to transfer balances, it should be enough to cover the high-interest debt you want to shift to this card.
It should also be sufficient for you to make the most out of those 21 billing cycles without interest being added. If the new refrigerator you want to buy costs $3,000 but your limit is only $2,000, you will either have to split the charge so some goes on another card, downgrade the appliance, or start saving.
You should also know that if you tap out all of your credit limit immediately and then let the balance sit there, it can negatively affect your credit scores. As I mentioned earlier, credit utilization is a significant factor in your FICO score.
Having at least 70% of the credit line unused is ideal, so if your card starts at $10,000 and you initiate a $3,000 balance transfer, you should be fine. Transfer $9,000, however, and you may want to drive the debt down faster, despite the 0% APR.
Who Should (and Shouldn’t) Apply
It should be immediately obvious that the primary advantage of the BankAmericard® credit card is its exceptionally long time period with no interest added to your revolving debt (or debt you transfer).
I would consider this card if you have expensive debt that you want to pay in increments without having to worry about financing fees. The balance transfer fee is 5%, but it can still save you quite a bit of money.
Here’s an example to get you going: If you have $5,000 on a credit card with an APR of 25% and you aggressively pay the debt down over 21 months of payments, it will cost you $1,225 in interest.
Your Goal
Should You Apply?
Here’s Why
Paying Off High-Interest Debt
✅
The exceptionally long 0% APR period on balance transfers allows you to pay down debt in increments without financing fees, easily offsetting the 5% transfer fee.
Financing a Large Purchase
✅
Provides a long, interest-free window to pay off major expenses (like home improvements or new electronics) over time.
Maximizing Credit Card Rewards
❌
The card does not offer any special perks, cash back, points, miles, or statement credits for purchases.
Traveling Abroad
❌
The card charges a foreign transaction fee, making it more expensive to use outside the country.
Conduct a balance transfer to this card, and the only cost to pay it off within the same time frame is the $250 transfer fee. That’s a pretty big incentive.
Another reason you might want to get this card is that you know you have large expenses in the near future. Whether you want to spiff up your home or purchase new electronics, a card that gives you such a long time to pay off those purchases can make a lot of sense.
But remember, the account’s APR will eventually go to the regular rate, so you have to prepare for that. Additionally, this card does not come with special perks or a rewards program.
If you’re looking for an account that gives you cash back, points, miles, or credits for certain purchases, the BankAmericard® credit card is not for you. Nor is it ideal for international travel because there is a foreign transaction fee.
Pros and Cons
I’ve said this before, and I’ll say it again: There is no perfect card for every person or situation. Each credit card account will have its benefits and drawbacks.
Here is what stands out to me as this card’s primary pros and cons:
Pros
21 billing cycles of 0% APR on purchases and balance transfers.
No annual fee or penalty APR for late payments.
Excellent mobile app and helpful customer service.
Cons
Doesn’t have a rewards program, so you won’t earn as you charge.
Doesn’t have a rewards program, so you won’t earn as you charge.
When evaluating any new credit card, first think about what you want it to do for you, and make sure you likely qualify before submitting an application.
The BankAmericard® credit card is great for expensive purchases you have planned or to paying down costly debt. And it’s worth keeping on hand after the 0% APR period expires because it doesn’t charge an annual fee.
Similar Cards Worth Considering
While the BankAmericard® credit card is a pretty straightforward tool, you may want to see what else is out there before you decide to apply. I don’t blame you, because the market is filled with credit cards for any situation or taste.
Here are a couple of options that offer some of what the BankAmericard® credit card offers, but that also have tradeoffs to consider:
Disclosure: When you apply through links on our site, we often earn referral fees from partners. For more information, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation for referrals for many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across CardRates.com (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Earn 20,000 bonus Points after spending $1,000 in the first 3 months of account opening.
0% Intro APR on balance transfers and purchases for 15 months; after that, the variable APR will be 18.74% – 28.74%, based on your creditworthiness. There is an intro balance transfer fee of 3% of each transfer (minimum $5) completed within the first 4 months of account opening. After that, your fee will be 5% of each transfer (minimum $5).
Earn 3 ThankYou® Points for each $1 spent in an eligible Self-Select Category of your choice (Fitness Clubs, Select Streaming Services, Live Entertainment, Cosmetic Stores/Barber Shops/Hair Salons, or Pet Supply Stores). Choose your eligible Self-Select Category on Citi Online or by calling customer service. The default Self-Select Category is Select Streaming Services.
Earn 5 ThankYou® Points for each $1 spent on Hotels, Car Rentals and Attractions booked on Citi Travel® via cititravel.com; earn 3 ThankYou Points for each $1 spent at Supermarkets, on Select Transit purchases, and at Gas & EV Charging Stations.
Earn 2 ThankYou® Points for each $1 spent at Restaurants; earn 1 ThankYou® Point for each $1 spent on All Other Purchases.
No Annual Fee
Intro (Purchases)0% 15 months on Purchases
Intro (Transfers)0% 15 months on Balance Transfers
Additional Disclosure: Citi is a CardRates advertiser.
With this card, you get 15 months of 0% APR on purchases and balance transfers. There is no annual fee, but there is a 3% foreign transaction fee. The balance transfer fee is just 3%, and you’ll have four months to initiate the transaction.
The Citi Strata℠ Card does have a rewards program, beginning with 20,000 ThankYou bonus points after you meet the minimum spend. You will also earn between one and five points per dollar, depending on what you charge.
However, the BankAmericard® credit card gives you a full six months more of interest-free purchases and transfers, so for straight interest charges, you can come out ahead with the extra time.
Disclosure: When you apply through links on our site, we often earn referral fees from partners. For more information, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation for referrals for many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across CardRates.com (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Earn a one-time $200 cash bonus once you spend $500 on purchases within the first 3 months from account opening
$0 annual fee and no foreign transaction fees
Earn unlimited 3% cash back at grocery stores (excluding superstores like Walmart® and Target®), on dining, entertainment and popular streaming services, plus 1% on all other purchases
Earn 8% cash back on Capital One Entertainment purchases
Earn unlimited 5% cash back on hotels, vacation rentals and rental cars booked through Capital One Travel
No rotating categories or sign-ups needed to earn cash rewards; plus cash back won’t expire for the life of the account and there’s no limit to how much you can earn
0% intro APR on purchases and balance transfers for 12 months; 18.74% – 28.74% variable APR after that; balance transfer fee applies
Looking for a cash back card with an interest-free period? The Capital One Savor Cash Rewards Credit Card may appeal to you.
You’ll get a $200 cash bonus after meeting the minimum spend requirements, and you will earn 1% to 8% cash back, depending on what you charge. There is also no annual or foreign transaction fee (which makes it good for global travel). You may like the Capital One shopping portals, too.
Compared to the BankAmericard® credit card, though, this card only gives you 12 months of 0% APR on purchases and balance transfers, which is a pretty sizable difference from 21 months.
Would I Recommend the BankAmericard® credit card?
If your primary goal is to buy expensive things now and avoid being charged extra on those purchases for almost two years, I would absolutely steer you toward the BankAmericard® credit card.
It eliminates the need to apply for a loan or use a Buy Now, Pay Later plan. Just swipe the card, and you’re in charge.
Same with balance transfers. When financing fees are frustrating you because so much of your payment is going toward interest, this card acts as a powerful cost-cutting tool thanks to its balance transfer offer.
There is no annual fee, so you can relax about that, too. Meanwhile, your transactions and account will be secure, and you’ll have access to an excellent mobile app that can help keep your money and credit on track.
What the BankAmericard® credit card doesn’t include is a program that lets you to earn cash, points, or miles as you charge. If that’s what you’re after, I recommend pairing it with a card that does.
But don’t minimize the major financial reward you would get with the BankAmericard® credit card. Avoiding sky-high interest fees can ensure that every dollar of your payment goes toward the principal. And that’s quite a perk.
BankAmericard® credit card
★★★★★ 4.6/5.0
BankAmericard® credit card
4.6/5.0
About this rating
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Erica Sandberg is a consumer finance expert and journalist whose articles and insights are featured in publications such as the Wall Street Journal, Reuters, MarketWatch, Forbes, and MSN Money. An experienced media host, she's led many financial programs, including her podcast, "Adventures With Money." She's appeared on Fox, CNN, "EconTalk" and "The Dr. Drew Podcast," and has been the resident money and credit authority for KRON-4 News in San Francisco for more than 10 years. She's the author of "Expecting Money: The Essential Financial Plan for New and Growing Families" and recipient of the 2024 Financial Literacy and Education in Communities (FLEC) Award for National Excellence.