
Writer: Eric Bank


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

If your credit score is struggling and money is tight, you may be looking at the best payday loans for bad credit. A payday lender can give you cash to cover the gap until your next paycheck, no matter your credit rating. Just be prepared for steep fees and high interest rates.
Or consider a short-term installment loan instead — it costs far less and is available from most of these lending services. The reviewed loan networks below will prequalify your loan request and find you an appropriate lender, all for free.
Online Payday Loans For Bad Credit
All seven online services can connect you to either a direct payday lender or a bad credit personal loan provider. They focus on helping those with subprime credit get a small loan for a short duration.
To prequalify for a loan, you must be at least 18, live in the United States, and have a reliable source of income, though the minimum amount depends on the lender.
1. MoneyMutual
- Short-term loans up to $5,000
- Online marketplace of lenders
- Funds available in as few as 24 hours
- Simple online form takes less than 5 minutes
- Trusted by more than 2 million customers
- Not available in NY or CT
Our top-ranked lender-connecting network is MoneyMutual due to its high approval ratings and variety of offerings. Notwithstanding your bad credit score, the company may be able to find you a small bad credit payday loan (as little as $200) if you will be receiving an income check within the next couple of weeks. Prequalification requires that you collect at least $800 a month from a reliable source, such as a job, pension, or Social Security.
2. CashUSA.com
- Loans from $500 to $10,000
- All credit types accepted
- Receive a loan decision in minutes
- Get funds directly to your bank account
- Use the loan for any purpose
Although CashUSA.comis located in Las Vegas, it can find you a loan throughout the United States, as permitted by your state. Its network is composed of tribal and state-licensed lenders that will work hard to approve your request for a short-term unsecured loan. If you collect at least $1,000 a month after taxes, CashUSA.com may be able to prequalify your loan request without a hard pull of your credit file.
- Loan amounts range from $500 to $10,000
- Compare quotes from a network of lenders
- Flexible credit requirements
- Easy online application & 5-minute approval
- Funding in as few as 24 hours
If your floundering credit score has you singing the blues, reach out to a warm welcome from BadCreditLoans.com. Based in Tacoma, the lender-connecting service can prequalify you for a loan if you can demonstrate a regular monthly income as well as a valid email address, phone number, and active bank account. The company’s lender network can arrange several types of loans, including a handy revolving credit line.
- Loan amounts range from $1,000 to $35,000
- All credit types welcome to apply
- Lending partners in all 50 states
- Loans can be used for any purpose
- Fast online approval
- Funding in as few as 24 hours
PersonalLoans.com can arrange a wide range of signature loan amounts and terms, all featuring APRs that beat those charged on payday loans. To receive no-credit-check prequalification, you must submit proof showing $500 or more of reliable monthly income. The PersonalLoans.com network offers additional services, including credit repair, debt settlement, and credit monitoring services.
- Loan amounts range from $100 to $1,000
- Short-term loans with flexible credit requirements
- Compare quotes from a network of lenders
- 5-minute approvals and 24-hour funding
- Minimum monthly income of $1,000 required
- Current employment with 90 days on the job required
CashAdvance.com, based in Utah, has been arranging payday loans since 1997 through its lender network. You can receive prequalification for a bad credit loan with full repayment due the next time you get paid. You’ll have to show the required minimum after-tax income of $1,000 per month and provide your phone number, email address, and bank account number.
What is a Payday Loan?
A payday loan (also known as a paycheck cash advance) is a way for workers with bad credit to borrow a modest amount of money over a short repayment term tied to their next paycheck, usually one or two weeks. It can come in handy as an emergency loan when you need money before your next payday. It is neither a secured personal loan nor a car title loan, but rather a loan based upon proof of your regular income.
You repay a bad credit payday loan in full on the due date, and typically, the lender will directly debit the amount from your checking account.
If you have insufficient funds in your account, you’ll be hit with an NSF penalty from your bank and late fees from the lender. You’ll then have to rollover your loan to your next pay cycle, triggering more fees and interest charges.
The main reason to get a payday loan is that your minimum credit score is much less important than your income. Some lenders may even skip a hard credit check as long as you can document enough reliable income to show you’ll be able to repay the loan on time. This is important because, unlike a secured loan or car title loan, a paycheck cash advance is an unsecured loan without the backing of collateral.
You may not be in a position to come up with a lump sum repayment of a payday loan due in one or two weeks. If so, consider an installment loan instead. This is a bad credit personal loan with a monthly payment term lasting three to 72 months.
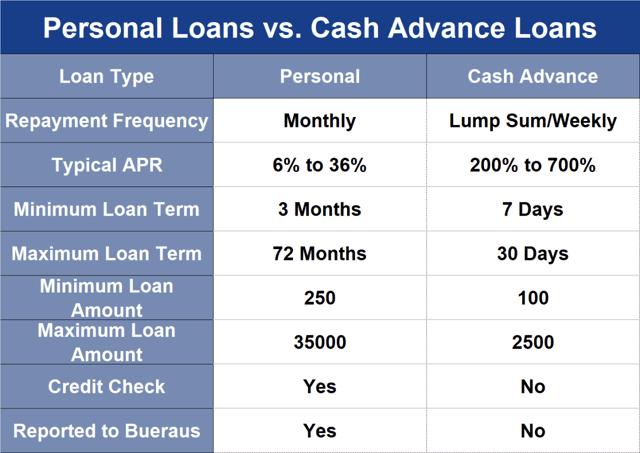
Typically, a personal loan charges a lower interest rate than that associated with payday loans but is more likely to require a credit check. A personal loan takes longer to repay, so the interest can mount up over time. Keep in mind that more than 80% of payday loans rolled over or renewed within 14 days, so they too can suffer from swollen interest charges.
Where Can I Get a Payday Loan?
While you could go to a local brick-and-mortar payday advance store to get your money in a few minutes, it may be more convenient to obtain your loan online if you can wait until the next business day.
Naturally, you must live somewhere reasonably close to a payday store to get an in-store paycheck cash advance. Some states outlaw payday loans, so getting one may require you to travel to a neighboring state.
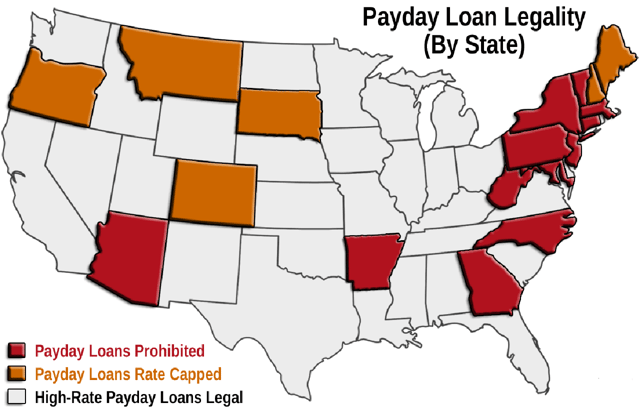
The online lender-connection services we’ve covered here have broad nationwide networks, making it possible for borrowers in most states to find a small short-term loan.
Most of the reviewed lenders provide personal loans instead of, or in addition to, payday loans. Only one, Utah-based CashAdvance.com, is strictly devoted to payday loans. MoneyMutualoffers both types of short-term loans.
Online payday loans are available in most states, but you’ll have to check with the lender to see if your state is eligible. The states of Connecticut, Maryland, Massachusetts, Pennsylvania, Vermont, and West Virginia never permitted payday loans, and the District of Columbia repealed its permission.
Can I Get a Payday Loan if I Have Bad Credit?
When you turn to an online lender-connection service, it’s typically assumed that you have bad credit. This review covers seven online bad credit loan services aimed at consumers with poor credit. They all follow a similar two-step application process for a paycheck cash advance or short-term unsecured personal loan: prequalification and application.
You can kick off the prequalification process by completing a loan request form or online questionnaire. This step does not require a hard pull of your credit files, and therefore will not affect your credit rating.
The prequalification step determines whether you meet the minimal requirements, which include:
- U.S. citizenship or permanent residency
- Being at least 18 years old
- Reliably collecting no less than the minimum required monthly income, subject to verification
- Having an email address, active checking account, and a telephone number
- Optionally, you may also have to provide your Social Security number and records showing your monthly payment for rent/mortgage and current debts
If you pass the prequalification step, the lending-connecting service will check its network for an appropriate direct lender that is the most likely to approve your request. You’ll then be transferred to the direct lender’s website and the loan application step will begin.
The direct lender’s application is usually more detailed than the prequalification form. In some cases, the connection service will prefill it with the information you already provided, so you’ll only need to add any missing details.
Some direct lenders perform a hard pull on your credit, while others don’t. A hard inquiry can trim your FICO score by five to 10 points, but the impact usually fades within a year.
If the lender approves your application, it will give you a loan option list containing the loan term, loan amount, interest rate, fees, and so forth. This is your opportunity to examine the fine print before signing the loan agreement. Within one to two business days, your loan proceeds will be deposited in your account at your bank or credit union.
There is always the possibility that a lender-matching service will be unable to find a direct lender willing to offer you a loan. Nonetheless, you may receive referrals to other debt service companies, such as those offering debt consolidation or debt relief.
Honest lender-connecting services never charge a fee. They instead make their money by collecting finders’ fees from direct lenders. Truthfully, it’s often said that payday loan interest rates are far too high even for a high-risk borrower, and we couldn’t agree more.
How Can I Get a Loan Without a Credit Check?
You may be able to get a loan without a credit check, but that option isn’t available everywhere. A credit check gathers payment history and other financial details, and some lenders use only a soft inquiry while others require a hard one.
- A soft credit check doesn’t harm your credit rating. When you check out your own credit rating, the inquiry will always be soft. This also pertains to credit checks run by parties other than those attempting, with your permission, to open a new account.
- A hard credit check is only used when you authorize a third party to open a credit account — a loan or a new credit card, for example — on your behalf. Most loan applications include fine print stating that your loan request automatically grants authorization to the lender.
While payday loans might skip the hard credit check, personal loans usually include one. For both types of loans, prequalification might only involve a soft credit check.
Bear in mind that prequalification doesn’t mean you’ll get the loan, but it certainly is a hopeful sign. The decision to approve or decline a loan application rests with the direct lender, not the loan-matching service. The lender is ultimately responsible for approving loans and setting terms.
A payday lender is more interested in your ability to repay a loan than your credit record. For bad credit consumers, payday loans may be easier to obtain than personal loans. However, if no credit check is done, you won’t have the opportunity to improve your credit score by having your on-time payment transactions posted to a credit bureau.
In other words, if you want the benefits of payment tracking from a credit bureau, you’ll have to submit to a hard credit check.
A no-credit-check loan usually carries a higher interest rate than loans that pull your credit. There’s nothing mysterious going on — when you ask a lender to ignore your credit history, you are admitting that the history is unfavorable.
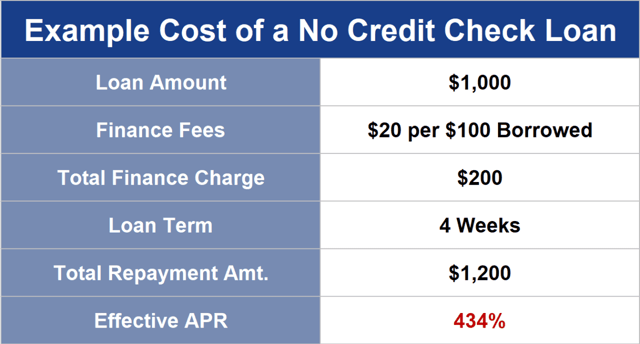
The higher interest rate compensates lenders for the greater risk they undertake by offering you a loan.
Are There Any Legitimate Online Loans For Bad Credit?
Our policy is to only review lender companies we deem as reputable, and the online loan providers we’ve evaluated above meet that standard. However, it’s important to acknowledge that some online lenders, like many companies, have faced challenges due to a few bad actors tarnishing the industry’s reputation.
Before you choose a payday loan lender, take a little time to check outside reviews and ratings. You can review the lender’s standing on the Better Business Bureau website and browse feedback on rating platforms like Trustpilot.
What Are the Signs of a Predatory Lender?
A predatory lender, often called a loan shark, uses abusive or unfair practices to dupe and intimidate a borrower. You can recognize predatory loans by the financial penalties they impose for late repayment. These can include astronomical origination fee charges and even higher interest rates.
Predatory lenders may also bury or twist the loan terms and approve loans they know will be difficult for you to repay. In many cases, they pile on outrageously high interest rates that target borrowers in urgent situations.
Here is a rundown of the seven worst signs of predatory lending:
- Four-digit interest rates: We’ve seldom seen a payday loan with an APR below 200%, and rates of 400% to 800% are common. Once rates exceed 1,000%, it becomes difficult to treat the loan as anything other than predatory. The highest APR we’ve seen so far was 2,200%. Make sure you read and understand a loan agreement before signing it. Don’t be confused by monthly interest rates masquerading as annual rates — APRs are the only way to compare different loans with each other. Astronomical interest rates can lead to a cycle of debt that is hard to escape. Often, the exit off this crazy train is bankruptcy.
- Additional costly services: Be on the lookout for items you don’t need, like credit insurance. Some lenders will push these added items, even making the loan contingent upon accepting the extras.
- Extra fees for bad credit borrowers: Your low credit score may affect your ability to get a loan, but it should not trigger extra fees. Watch out for the old bait-and-switch, where the payday loan lender claims at the last minute that you don’t qualify for the loan you wanted, instead steering you to a costlier product with higher fees. To combat this type of abuse, know your credit score and credit report contents before applying for a loan.
- Asking for collateral: Payday loans are predicated on your ability to repay the loan in full when you next get paid. Asking for collateral, a practice that the Federal Trade Commission calls equity stripping, should not be part of the equation, and can simply be a way for the lender to strip you of your home or car. If you want to use collateral, you’d be better off seeking a home equity loan or cash-out vehicle refinancing loan, both of which will charge much less interest. Whenever you post property for a secured personal loan or payday loan, you run the devastating risk of losing a vital asset.
- The bum’s rush: Your spidey sense should tingle whenever a lender tries to rush you through the paperwork. It’s your right to read through the loan agreement and any associated documents before affixing your signature. Doing so helps you understand whether you can afford the loan and to uncover any terms in conflict with the lender’s verbal representations. When lenders hurry you to sign, they may be trying to cover up unfair terms and undisclosed fees. Also, be careful when the lender asks you to sign a second set of documents because they may have terms that differ from the original. Don’t allow critical fields to be left blank, as the lender may go back afterward and fill them in to modify the agreement.
- Foul rollovers: Many payday loan borrowers roll over their loans because they can’t repay them on time. Typically, payday lenders charge a fee for rollovers. But be on the lookout for higher interest rates when you renew the loan. Sure, a 400% APR is bad enough, but 1,200% or 2,400% are ridiculous. They can become a one-way ticket to destitution and a rendezvous with a bankruptcy judge.
- The big lie: Outright lying is the absolute proof of a loan scam. This may be accompanied by pressure to sign a loan agreement without being shown the legally mandated loan disclosures. It’s equally crooked for a lender to ask you to lie on your loan application form to help win loan approval. For example, the lender may ask you to invent income you don’t really have. You are aiding and abetting fraud if you go along with these purposeful misrepresentations, and that may land you in a world of trouble.
The Consumer Financial Protection Bureau (CFPB) has taken action against lenders for bullying payday borrowers into a “cycle of debt.” According to CFPB Director Richard Cordray:
“This culture of coercion drained millions of dollars from cash-strapped consumers who had few options to fight back. The CFPB was created to stand up for consumers and today we are taking action to put an end to this illegal, predatory behavior.”
However, in July 2020, the CFPB removed a rule that had required lenders to verify borrowers’ ability to repay their loans on time. We’re optimistic that the CFPB has strengthened its oversight again following the change in administration in 2021.
If you feel you’ve been victimized by a predatory lender, you can file a complaint with one or more state and federal agencies.
What Are the Disadvantages of Payday Loans?
Payday loans come with high APRs and hefty fees. They won’t fix a long-term money problem and can leave you with fewer resources to improve your finances. Rollovers are common, and the added costs can grow close to the amount you originally borrowed.
You also need to spend time documenting your income and any other information requested by the lender. Some of this information could be sensitive, and you certainly don’t want it to be hacked and scattered online.
Compare the Best Payday Loans For Bad Credit
Our survey of the best payday loans for bad credit shows that you have options despite a less-than-stellar credit rating. The seven reviewed lender-matching companies provide you the opportunity to quickly obtain cash when you need it.
If possible, consider a short-term personal bad credit loan instead of a payday loan — the terms are friendlier, and they are easier to repay.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author