
Writer: Erica Sandberg


Editor: Jon McDonald


Reviewer: Ashley Fricker

We deploy a step-by-step methodology to each piece of research we publish to ensure our studies offer complete coverage and meet our rigorous editorial standards.
Who doesn’t want to be rewarded for their work? And if work means spending with your credit card, surely you want to be rewarded for that too.
When your account is equipped with a program that gives you cash back as a percentage of what you spend or as points or miles, you can definitely come out ahead.
Since there’s so much competition in the credit card space, it makes sense for companies that issue them to capture not just your attention when you’re looking for a new card, but to keep the rewards flowing with your regular charging habits.
To keep these programs fresh and enticing, credit card companies monitor what consumers want out of their rewards and how they manage them. Here are 39 fascinating recent statistics about credit card rewards.
1. More Than 80% of Cardholders Ages 18-24 Earn and Use Rewards
Honestly, this is great news. That so many credit card holders are racking up at least some rewards on their accounts and then trading them in for the things they want and need means that consumers know this option to profit with their plastic exists.
Percentage of Cardholders Ages 18-24 Who Earn/Use Rewards
Source: Taxpayers Protection Alliance Survey
This poll found that credit card rewards are particularly important to younger consumers, too, with people ages 18 to 29 being a touch more (at 82%) apt to earn and use their rewards.1
Why? Typically, they are lower-income earners, so maximizing their rewards, even by a few dollars, can really help stretch a budget.
2. 68% of Primary Credit Card Users Rank Cash Back as the Most Appealing Perk
Credit card rewards that come in the form of cash back, as opposed to points or miles, are certainly popular.2 That makes sense because cash back is incredibly simple. All you need to do is use your credit card to make purchases, and the issuer gives a percentage of what you charge back to you.
When you're ready, you can spend what you've earned, whether as a statement credit to drive your balance down, to buy a gift card, to shop on sites like Amazon, or to have that money delivered to your bank account.
3. 51% Call Flat-Rate Cash Back on Everything 'Very Appealing'
There are two basic options for cash back rewards. The program might be tiered, where you earn a higher percentage in some categories and a lower one in others.
For example, you might earn 3% on things like dining out and supermarkets, 2% on subscription services and rideshares, and 1% on everything else.
If you strategize your charges in the right way, you can come out ahead. However, a flat-rate cash back card is more appealing to cardholders.2
You don't have to plan ahead; just use the card, and you will get the same rate, such as 2% on everything you buy with the card.
4. About 3 in 4 Households Earning Under $50,000 Say Cash Back Is Their Preferred Reward
When every dollar counts, a cash back card can make a huge difference in making ends meet.
Households Earning under $50K That Prefer Cash Back Rewards
Source: Taxpayers Protection Alliance Survey
According to this research, 67% of working-class cardholders say credit card rewards are important to their household finances.1
Think about it this way: If you are struggling to put food on the table and spend $1,000 a month at the grocery store and on other necessary household items, a credit card that gives you 2% back means $20 in your rewards bank.
That could help offset the cost of a water bill or a renters' insurance premium.
5. 4 In 10 Say Identifying or Redeeming Rewards Through an App Encourages Them To Spend More
You know that rectangular thing you hold in your hand that does pretty much everything you need to do, from making calls to searching for the closest EV charging station? If you have the credit card company's app on that mobile device, you may be spending a little more on your card just to get the rewards.
According to this research, rewards-focused consumers are more likely to spend more if the app makes it easy to identify deals and redeem rewards.3
If you feel that you are constantly checking the app and it's motivating you to spend just a little more to get ahead, you might want to hide it in a folder so that it's not so alluring.
6. Nearly Half of Cardholders Say Earning Rewards Is a Top Reason They Use Their Card
What's the use of having a credit card that offers a robust rewards program if you're not going to use it? Roughly half (48%) of credit cardholders are taking advantage, which is great.4
But it's important to be careful so you don't charge too much and get into debt. If you don't pay off the balance before interest is added, the value of all those hard-earned rewards will be reduced or eliminated.
Check your balance before charging, and make sure you can repay the bill in full before it comes due. The easiest way is to enroll in automatic bill pay with the credit card issuer and select the “pay in full” option.
7. 79% Have Used Their Points for Statement Credit in the Last Six Months
I absolutely love this statistic because it can make a significant positive financial difference. Sure, you can trade your rewards in for all kinds of things, from travel to gift cards.
| Cardholder Redemption Style | Percentage |
|---|---|
| Used Points for a Statement Credit in the Last 6 Months | 79% |
| Use Points Immediately for Everyday Expenses | 36% |
| Saving Points for a Big/Dream Redemption | 37% |
However, if you are like the majority of cardholders, you use the value of your points to drive your credit card balance down.5 So, if you have points worth $300 and your credit card balance is $400, you can simply apply them and reduce the debt so that it's only $100.
No navigating complicated portals or searching for things to buy with the points. It's a simple and effective way to reduce debt.
8. About 3 In 4 People Would Choose a High APR Rewards Card Over a Low-Rate Card Without Rewards
This shows just how valuable a credit card rewards program can be. All credit cards have an APR, even if it is waived during an initial 0% interest promotional period. Eventually, it will be part of your account.
Then, if you revolve a balance instead of paying the entire debt off by the due date, financing fees will start to accrue. The higher the APR, the more it will cost you.
Yet the vast majority of cardholders say they would rather have a high-APR card with a great rewards program than one without.5 And why not? If you pay your debt in full, you'll always come out ahead.
9. 63% of Voters Would Rather Keep Their Rewards Than Give Them Up for Lower Prices
I found this statistic, gathered from a survey of registered voters, particularly fascinating. As inflation rises but incomes don't keep pace, there is less money available to cover basic expenses and any extras.
That can put tremendous pressure on a low- to mid-earning household. However, by a substantial margin, people say they would prefer to keep their credit card rewards program intact over a store lowering its prices.1
This indicates just how much people value the credit card rewards they earn when they shop, considering the process a cost-saving technique.
10. 65% of Americans Believe Their Rewards Are Not Keeping Up With Inflation
On the other hand, there are certainly many people who know that the value of their credit card rewards is no match for rising inflation.6 When the cost of goods and services escalates, the impact on your wallet can be severe.
| Question | Responded "Yes" | Responded "No" |
|---|---|---|
| Are Rewards Keeping Up With Inflation? | 35% | 65% |
| Are Rewards Programs Fair? | 63% | 37% |
Earning $20 a month in cash back rewards is marvelous, especially because all you had to do was charge expenses and pay the bill in full, but that joy can be tempered when a loaf of bread that normally costs $4 is now $6.
Still, it's a reward of cash you didn't have before, so you may as well be happy for it.
11. Nearly 40% Think Credit Card Rewards Programs Are Unfair
If you get annoyed by redemption restrictions, 37% of Americans agree with you.6 Most credit cards require you to reach a minimum balance of $25 in cash back or accumulate 1,000 points before you can redeem the rewards.
Or maybe you lose some of your rewards because your account is not in good standing. That can feel unfair.
If you have the wrong tiered rewards credit card for your lifestyle, you may only be earning the bottom rate because the things you need to buy to reach the highest rate are just not part of your life.
The solution? Get the right card for you and understand the program before you go into it.
12. No-Rewards, No-Annual-Fee Cardholders Reported the Lowest Satisfaction
Basic credit cards are available and can be a wonderful way for people with damaged credit or no credit to start. They tend to be very easy to qualify for, and some have no annual fees.
Once you have the card, you can use it to build a strong credit history. The problem is, if it doesn't have a rewards program, you may be a less-than-enthusiastic cardholder..7
On a 1,000-point scale, cards with no annual fee and no rewards program scored the lowest satisfaction rating at 573.
But if you have one of these cards, don't let it get you down. When your credit scores are in a better place, you'll be in a better position to get a card that comes with the rewards program you like. Just give it time.
13. Only 29% of Customers Say Their Card Use Maximizes Reward Earnings
This is not a great statistic. It means that 71% of cardholders are not getting everything they can from their credit card rewards program.7
Why leave value on the table? Yes, it can take time to figure out these programs so you can maximize the rewards. In general, this says to me that there is a mismatch.
A flat-rate cash back card takes virtually no effort, as opposed to a points- or miles-based card that has fluctuating rewards rates. It's important to get the right card for you and your habits.
Just because you're eligible for a premium card with a generous rewards program doesn't mean it's a good match.
14. 16% of Cardholders Find Rewards Programs Confusing
Who teaches you how to use a credit card rewards program? Probably no one, not your college professor, and perhaps not even your parents.
Even your credit card issuer might not give a straightforward guide on what the program really is and what you can do to turn a profit.
The truth is, some aspects of credit card reward strategies, such as point transfers, can be a little complicated. In fact, 16% of cardholders say rewards programs are the most confusing aspect of credit cards.4
But a little knowledge goes a long way. Take time and learn. You can do it!
15. 36% of Consumers Use Rewards to Offset Everyday Expenses
Once you have hit the minimum number of rewards that you can extract, you're free to use them, and more than a third of cardholders do.5 There is often no reason to wait.
They don't earn interest; they're just there for you, so go ahead and use them for the things you need. Stocking the kitchen, buying gas for the car, and paying for household utilities can be expensive, but they are also essentials.
So if you are like a good portion of Americans who are applying their credit card rewards to these expenses, great. It's a sound financial decision.
16. About 4 in 10 Are Saving Rewards for “Big” or “Dream” Redemptions
Conversely, if you're more interested in banking your rewards so that you have enough for something really special, 37% of cardholders agree with you.5
For motivation, here's an example. Let's say you have a cash back card that earns you 2% on everything. You spend $1,500 every month because you put everything you can on your card and pay it off in full.
Just for doing that, you'll have $360 in cash back to use on that dream purchase.
Or if you accumulate 100,000 miles, they might be worth between $1,000 and $2,200 in travel redemption.
17. Gen Z Redeems Points the Fastest (72% Don't Wait)
I could guess that the reason the highest percentage of cardholders who redeem their credit card rewards points on a monthly basis (or as soon as possible) are the youngest cardholders is that they're impetuous.
But it's more likely that they have less money to work with, so they use the extra financial help whenever possible. Waiting is more of a luxury. The difference in age groups is pretty extreme.
Just 33% of cardholders ages 45 to 54 redeem their points so quickly, and 51% of cardholders ages 25 to 34 say they do the same.5
18. Losing Rewards Due to Government Controls Would Disappoint 63% of Cardholders
You would be in the majority of American adults if you believe that having access to a credit card is important because it helps you manage your household finances.
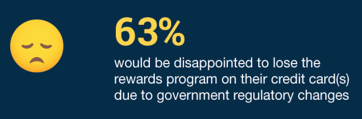
But many people are also concerned about the potential impact of government price controls on their credit card rewards programs.
Add those who would be very disappointed (38%) to the 25% who would be somewhat disappointed if changes do affect this benefit, and that figure reaches 63%.8
I'd be disappointed, too.
19. Most Travelers (67%) Want Cheap Airfare or Hotels Over Perks
It definitely makes sense to use a credit card that is either co-branded with an airline you like, for complimentary bag check and other benefits, or a general-purpose travel card for flexible perks.
It's not only financially smart; it can also make the entire experience more comfortable. But if you're seeking the cheapest airfare possible (as about 7 in 10 cardholders do9), you may also be willing to forgo cards with luxury perks like airport lounges if it means getting a better airfare or hotel deal.
Unfortunately, this is not something you can control, but you can use your travel card to earn points or miles. They'll be good for your next trip, helping lower the cost of that adventure.
20. Co-Branded Miles Cards Don’t Appeal to 30% of Consumers
There definitely seems to be a shift moving away from complicated credit card rewards programs.
This study also found that younger cardholders are definitely interested in building their credit history, but not in pursuing such traditional travel perks as rewards for hotel rooms.2
A co-branded card associated with a specific airline or hotel brand can also feel more restrictive than a general-purpose travel card, which offers greater flexibility.
Both have a place, of course, but you need to know your travel style before applying for the card that will get you where you need to go.
21. Everyday Earning Tops the List of Perks for 47% of Travelers
This statistic should resonate with many travelers. Being able to accumulate as many points or miles as possible to trade in for future travel is what's most desired, by a lot.
The next most valued quality in a credit card rewards program is statement credits, but that falls to only 12.3%.10
I must admit I was a little surprised to find that only 7.3% of travel cardholders value welcome bonuses the most, and a mere 4.4% say airport lounge access and TSA PreCheck credits are the most important to them.
Then again, last time I was in an airport lounge, it was more crowded and louder than the area at the gate.
22. Premium Travel Card Satisfaction Is Highest Among Airline Co-Branded Cards
Although this may seem to contradict the low desirability of co-branded travel credit cards in the previous statistic, once people have these products, they tend to like them.7
Satisfaction is largely driven by the travel benefits and exclusive experiences the cards offer, not just the monetary rewards for charging expenses.
If you enjoy extras such as potential upgrades and boarding the plane first, and you like the airline and where it flies, a co-branded card can make your travel time far more pleasurable.
23. Sign-Up Bonus Is Reason Enough for 22% of Leisure Travelers to Open a New Card
Opening a new credit card just for the huge welcome bonus can certainly work in your favor, and nearly 1 in 4 leisure travelers agree.9 Some of the deals are incredible, such as 100,000 points or miles into your rewards bank just for spending a certain amount of money within a few months.
If you can meet that minimum spend, which may include booking a trip with flights, accommodations, and car rentals, you may automatically be in line to get that bonus.
My only hesitation here is accumulating too many credit cards. Applying for one each time you take a big trip can result in plastic overload. Remember, each account needs to be managed and monitored.
24. Daily Spending Drives Rewards for 31% of Active Travelers
Want to boost your travel credit card reward accumulation? Use it for everything you can, as 31% of active travelers say they do.9
Household expenses such as cellphone, cable, and internet bills, electricity, gas, water, streaming services, insurance premiums, car maintenance, and kids' expenses are just a start.
As long as you keep the balance at zero, you can rack up an enormous amount of points or miles and profit from the process.
If you spend $2,500 every month on a credit card that gives you 3X points, in six months you'll have 45,000 points, which could be worth more than $500 in travel redemptions. It's a wise strategy.
25. Only About 43% of Travel Cardholders Have Ever Transferred Points
I have to admit that I completely understand why a substantial number of people (42.9%) who have travel credit cards do not transfer their points to an airline's or hotel's loyalty program.10
Once you move those points or miles, you can't go back, so you have to be very sure you will be taking a trip and staying with that hotel or flying on that airline.
On the other hand, this redemption method can yield the highest value, giving your rewards far more bang for the buck. If you have the option, in the right circumstance, it's worth taking.
26. 45.1% of Travel Card Holders Have Let Rewards Expire
In general, credit card rewards stay good until you use them. There are some situations when they do expire, though, and it's rather shocking to learn that nearly 50% of people who have travel cards have lost their points or miles.10
Cardholders Who Have Let Rewards Expire
Source: BestMoney survey
This can happen if you transferred your points or miles to an airline's or hotel's loyalty program. When you do, they become subject to that company's specific expiration rules.
You can also lose those rewards by closing your card before transferring or redeeming them, or by falling behind on your monthly minimum payments.
27. 44.6% Say They Don’t Have a Travel Card Because They Don't Travel Enough
There is no reason to get a travel card if travel is not in your future. Other credit cards will have rewards programs that are more suitable for your needs.
However, there are other reasons people decide not to get a travel credit card when they might want one. About 35% believe the annual fees aren't worth it.10 While this can be true, some travel cards have very low annual fees, and others have none at all, so shop around!
Another 18.4% say there are too many options and it's confusing, and 13.5% say they didn't realize a travel rewards card might be a good fit for someone like them.
28. Nearly Half of Cardholders (47%) Rank Fraud Protection in Their Top Three Benefits
No one wants to be a victim of identity theft or fraudulent activity. It not only feels terrible when it happens, but clearing up the damage can also take a lot of time and effort.
Therefore, it makes sense that so many people value fraud protection even higher than credit card rewards.11
| Benefit | Percentage of Cardholders that Ranked it in Their Top 3 |
|---|---|
| Fraud protection | 47% |
| Earning rewards | 41% |
| Emergency access to credit | 40% |
| Convenience | 39% |
The good news is that almost all credit cards are embedded with excellent protection. These may include real-time alerts when a suspicious purchase is made with your card, the ability to instantly lock your card in the app, and virtual card numbers that can't be replicated.
Most issuers also offer zero-liability fraud protection, so you won't pay anything for unauthorized charges.
29. Consumers are Projected to Earn About $60 Billion in Credit Card Rewards In 2026
It's really quite amazing how much money is handed over to consumers just for using a credit card.12 But you may wonder just who pays for all those rewards programs, and the answer is a variety of sources.
Interchange fees are a big one. Every time you use your credit card, merchants pay somewhere between 1.5% and 3.5% of the transaction. Credit card companies also use revenue from interest charges, annual fees, and penalties.
It all adds up. The deal will always be in your favor, though, when you manage your account in just the right way. Pay on time, pay in full. Yes, it's that simple.
30. Consumer Credit Cards Average $272.50 in Welcome Cash
It's always interesting to compare credit card products. The sign-up bonus for a small business card is typically larger than for a consumer credit card.
On average, a credit card you get for yourself comes with about $270 in cash back rewards once you reach a certain spending threshold.13
Average Welcome Bonus for New Credit Cards
That's a decent sum of money simply for spending enough within the first few months to get it.
Always think about what you need before you apply, because you don't want to be stuck in the last few days buying something unnecessary just to get the bonus.
31. Only 28% of SMB Owners are Willing to Pay an Annual Fee to Earn Rewards
If you have your own business, you may be operating on very tight margins, which means an annual fee may be more than you are willing to spend to get a rewards card.14
But there are plenty of credit cards available to small business owners that do not charge a high annual fee, and some have no annual fee.
You can always add a credit card with more robust rewards and perks to your portfolio when you are in a better financial position and can afford the fee. You may never need it, but it's an option.
32. Rewards Redeemers Outspend Non-Redeemers by 107%
If you have a credit card you use often and charge large amounts, you are a highly valued cardholder. It's one of the reasons a rewards program is part of so many accounts.
This study shows that cardholders who redeem their points or cash back often spend considerably more money overall and make far more individual purchases than cardholders who seem to forget their rewards exist.15
Essentially, the more you use your rewards, the more you will likely swipe your card. That’s exactly what a credit card company wants: regular, responsible cardholders.
33. 1 in 3 Would Switch Banks for Better In-App Offers
You might have noticed your credit card is not just a payment tool. In many cases, it can help you get personalized savings. 16
A Mastercard study found that one in three consumers would switch credit card companies just to access to the rewards and discounts offered by their favorite businesses.
As a cardholder, you can expect your credit card app to provide instant savings from the dashboard. So if you're able to score 25% off at stores where you shop often with one card over the other, you just may decide to switch.
Credit Card Rewards are Popular For Their Flexibility
Clearly, you can benefit from a credit card in more ways than just facilitating safe and secure payments. But you can also get a lot out of the account if your card has a rewards program.
Should you get one that offers cash back, points, or miles? Interested in something super simple, or would you prefer to be a strategist? As a consumer, you have so many choices; get the best match and manage it well.
Do so, and the rewards you earn can definitely work out in your favor.
Data Sources
1 https://www.protectingtaxpayers.org/congress/new-poll-credit-card-rewards-are-vital-budget-tool-for-working-class-middle-income-and-young-voters/
2 https://www.creditonebank.com/articles/why-younger-consumers-see-credit-cards-differently
3 https://www.pymnts.com/wp-content/uploads/2026/04/PYMNTS-Intelligence-Winning-Top-of-Wallet-April-2026.pdf
4 https://www.citigroup.com/rcs/citigpa/storage/public/US-consumer-cards-credit-trends-survey.pdf
5 https://cdn.prgloo.com/media/3c7775836fbe42b5b3ecdd6bae711bb0.pdf
6 https://wallethub.com/blog/credit-cards-rewards-survey/63067
7 https://www.jdpower.com/business/press-releases/2026-u-s-credit-card-satisfaction-study/
8 https://www.aba.com/about-us/press-room/press-releases/new-data-americans-oppose-changes-that-threaten-credit-card-reward-programs
9 https://www.forbes.com/advisor/credit-cards/travel-rewards-in-2026-what-vacationers-want-use-and-find-frustrating/
10 https://www.bestmoney.com/credit-cards/learn-more/travel-credit-card-rewards-survey
11 https://www.aba.com/about-us/press-room/press-releases/morning-consult-survey-spring-2026-fintechs
12 https://www.marketresearch.com/Freedonia-Focus-v3334/Rewards-Credit-Cards-Currency-Types-45575618/
13 https://wallethub.com/answers/cc/what-is-the-average-cash-back-rate-for-credit-cards-2140871192/
14 https://www.pymnts.com/credit-cards/2026/why-small-business-owners-still-reach-for-personal-cards/
15 https://www.amplifiloyalty.com/blog/from-retention-to-revenue-unpacking-amplifis-2025-performance-highlights
16 https://www.mastercard.com/us/en/news-and-trends/Insights/2026/turn-everyday-transactions-into-lasting-loyalty.html
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author