
Writer: Eric Bank


Editor: Lillian Guevara-Castro


Reviewer: Ashley Fricker

Are you considering applying for a Discover credit card? Then you’ll want to know which credit bureau Discover uses because that’s where you should first review your credit report.
It’s always smart to check your credit reports for errors because if you successfully dispute a negative item, your credit score may improve right away. And of course, a higher score can make it much easier to qualify for the credit card you want.
Discover Uses Equifax the Most
Discover uses all three of the credit bureaus — Experian, TransUnion, and Equifax — to check your credit when you apply for one of its cards. However, research indicates that Equifax is first among equals.
One study using data from 2014 onward found that Discover uses Equifax was about half the time, while the other two credit bureaus each received about a quarter of credit inquiries. Of the 448 data points, Equifax accounted for 233, Experian had 112, and TransUnion had 103.
Although Equifax was the most popular, pull destinations varied by state. Therefore, it’s useful to know the statistics for your state before you apply for a Discover card.
For example, TransUnion was the most popular in Vermont, Wisconsin, and Arkansas, and Experian led in Nebraska, Idaho, Illinois, and Hawaii.
Another study used data representing 134 credit report pulls by Discover in 2016 and 2017. It confirms that Equifax is Discover’s favorite credit bureau. This study doesn’t publish the statewide numbers but does reveal the most commonly used credit bureaus in each state’s dataset.
Hard credit pulls happen when a lender reviews your credit after you apply for new credit, and they can affect your score. In many cases, your FICO score may fall by five to 10 points after an application. That dip shows up at the credit bureau that received the inquiry.
That’s why it’s important to clean up the relevant credit report because you may be able to counteract the score drop by correcting a derogatory error. Equifax, and indeed all three credit bureaus, have formal procedures for correcting errors.
Which Credit Bureau Does Discover Report to?
Let’s be clear: Discover not only pulls credit histories when evaluating new applicants, it also reports payment information to credit bureaus when you use your Discover card. It reports items like your credit balance, credit limit, and payment history, which the bureaus use to compute your FICO scores.
Although all three bureaus use the same FICO scoring system, scores often vary among bureaus. One explanation may be that Discover pulls more frequently from Equifax, implying that your Equifax FICO score may be slightly lower due to the impact of hard pulls. In addition, activity reported to just one or two bureaus can easily cause scores to vary.
In general, Discover does not reveal which credit bureaus receive its activity data. Discover offers its Credit Scorecard as a free benefit to any of its cardmembers. This service lets you check your FICO score at any time. Discover says the FICO score you receive comes from TransUnion and is based on a snapshot of the data currently found on your TransUnion credit report.
Don’t assume you’ll get the same score from Equifax and Experian. As mentioned earlier, the scores from the three major bureaus often vary. However, the scores should be relatively close to each other if Discover reports payments to all three bureaus.
You may have to pay Equifax and Experian to get you the FICO scores they assign you. Be wary of sites that offer to get you your credit scores for free, as they will often give you a proprietary score rather than FICO’s.
What Credit Score Is Needed for a Discover Card?
We’ve taken a hard look at the FICO score you need to obtain a Discover card. Our findings suggest that you need a minimum score of 648, according to at least one source. Most sources indicate a FICO score in the range of 680 to 720 will be enough to get a Discover card.
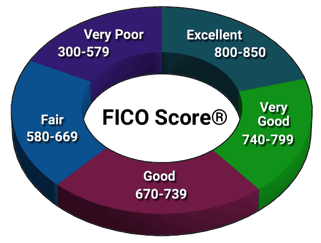
That being said, credit card companies usually don’t write a minimum score in concrete. A lot can depend on the particulars of your credit history, your income and expenses, and whether the card is secured.
It’s widely reported that Discover carefully reviews your overall credit profile rather than just your FICO score when considering your card application. This can work both ways.
For example, if you have certain red flags in your credit history, Discover may reject your application even if you have an acceptable score. On the other hand, if your derogatory items are old, Discover may be willing to give you the benefit of the doubt even if your score is on the low side.
If you don’t qualify for an unsecured Discover card, you can apply for a secured card from another issuer such as the Capital One Platinum Secured Credit Card to rebuild your credit first. This card reports your payment activity to all three credit bureaus, so it’s your opportunity to boost your FICO score by making all payments on time.
This card is easier to obtain because you deposit refundable cash collateral in a locked account. This removes the risk that you won’t pay on time, as Capital One will use the account to ensure it receives timely payments.
Your account balance determines your credit line up to the card’s limit. With a clean record, you should eventually be able to replace this card with an unsecured one and recoup your deposit.
How Often Does Discover Raise Your Credit Limit?
Discover doesn’t explicitly reveal its policy regarding raising your credit limit. However, anecdotal information is available from many sources. In fact, one of our editors reports that her Discover card, which she said she’s owned for one and a half years, has already given her an automatic increase.
Automatic increases are best. The reason is that you will not be charged with a hard pull when the credit card company reevaluates your credit. In contrast, when you request a higher credit line, Discover will require a hard pull that can damage your score.
Now, asking for an occasional increase for one of your cards won’t have a substantial impact on your score. However, if you make requests to multiple cards, your score could be significantly hurt, as it indicates a need for more credit that may be due to financial distress.
You can take a few steps that may encourage your card issuer to review your credit limit without you having to ask. One of the easiest is to update your card company when your income goes up or your regular expenses go down.
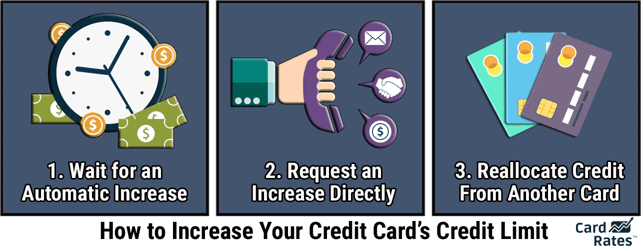
Many credit card websites allow you to maintain your personal profile that includes your annual income online. Make sure you include secondary sources of household income, such as Social Security or retirement account benefits, student financial aid, and self-employment income.
It also helps to lower your credit utilization ratio (CUR), which compares how much credit you’re using with how much you have available. A meaningful drop, such as going from above 35% to below 20%, shows stronger credit habits and may help trigger an automatic credit limit increase.
Inspect Your Reports and Dispute Mistakes
The answer to “Which credit bureau does Discover use?” is Equifax. Discover uses Equifax for about half of the requests it gets for a hard inquiry, dividing the other half equally between the two other credit bureaus.
In general, when applying for a new credit card, you should inspect your credit reports and dispute any mistakes, thereby helping to boost your score. By knowing which credit bureau the credit card company favors, you can concentrate on that bureau’s credit report first.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author