
Writer: Eric Bank


Editor: Lillian Guevara-Castro


Reviewer: Adam West

Our experts and industry insiders blog the latest news, studies and current events from inside the credit card industry. Our articles follow strict editorial guidelines.
Key Takeaways
- Gemini rolled out a U.S.-only credit card that offers up to 4% back in XRP, with no annual or foreign transaction fees.
- Ripple USD’s (RLUSD) integration shows how stablecoins are gaining prominence in mainstream payments.
- Since the passage of the GENIUS Act, cryptocurrencies such as Gemini are entering mainstream financial services, driving new competition.
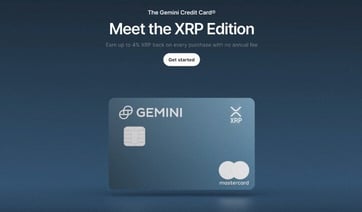
Gemini, the crypto exchange founded by the Winklevoss twins, launched its XRP Edition Credit Card recently.
Built in partnership with the blockchain company Ripple, issued by WebBank, and with Mastercard as its payment network, the card targets U.S. consumers who want cash back rewards paid directly in cryptocurrency, specifically the Ripple Protocol’s native currency, XRP.
Gemini’s announcement comes amid the wider industry move on the part of the cryptocurrency companies toward consumer finance. The exchange seeks to incorporate digital assets even further into everyday payments citing the vibrant XRP network of Ripple when it comes to unveiling its competitive advantages.
Cardholders can earn up to 4% back (capped at $300/month) on EV charging, rideshare, and fuel purchases, along with tiered perks of 3% on dining, 2% on groceries, and 1% on general spending. The card carries no annual fee, no foreign transaction costs, and no conversion fees when redeeming rewards.
Broadening Crypto’s Applications
In the card launch, Gemini introduced support for the stablecoin Ripple USD (RLUSD), which is pegged to the U.S. dollar. It is a base currency for U.S. trading pairs. RLUSD shot to one of the top six USD-backed stablecoins by market cap, around $640 million.
Onboarding to Gemini simplifies trading, streamlines conversions, and opens the prospect that crypto products will be the competition to traditional financial systems.
The adoption by RLUSD represents a broader development for card issuers: Consumers may now think of digital assets less as speculative and more as practical payment instruments. The inclusion of stablecoins into settlement and reward mechanisms may hasten the product adoptions associated with cryptocurrencies. It was a bet on changing conditions.
Gemini’s release of the XRP card reflects the pressure to stand out in an increasingly crowded market. The company had a net loss of $282.5 million during the first six months of 2025.
It is preparing the groundwork for a U.S. IPO financed by a $75 million credit line held by Ripple that is expandable to $150 million.
Crypto trade levels are cooling off, and Gemini’s expectation is that consumer-facing strategies — especially those tied to vibrant communities such as the “XRP Army” — will encourage loyalty and generate repeat revenue.
Mastercard’s participation in the collaboration marks the increase in openness among traditional networks toward the enabling of crypto-based reward payments. That breakthrough was made possible due to regulatory clarity granted under the GENIUS Act.
Post-GENIUS Act Competition Persists
The Gemini XRP card comes less than two months after the passage of the GENIUS Act, the regulatory road map outlining the way the crypto products will fit into everyday money.
Since the GENIUS Act took effect, Coinbase, Binance.US, and Kraken have each issued their respective products, which blur the line between fiat and crypto. Coinbase, for instance, rewards its cardholders with up to 4% back in bitcoin.
Gemini’s 4% XRP rewards are aimed at highly engaged crypto users while also broadening the card’s appeal to wider market segments.
As card companies and crypto platforms rush to gain early users, the businesses that blend crypto rewards with traditional card programs may be getting an early adopter advantage when it comes to appealing to digitally savvy consumers.
Challenges remain, from compliance hurdles to the volatility of reward assets like XRP.
What It Means for Card Issuers
Gemini’s XRP Edition card provides several insights for credit card professionals:
- Innovation is needed to thrive: Attributes, such as cryptocurrency cash back, may attract attention and stimulate additional response.
- Stablecoin adoption is gaining speed: RLUSD’s prospects foreshadow a future when stablecoins will underpin conventional systems of payments.
- Scale is fueled by partnerships: Collaboration among crypto companies and incumbent networks, such as Mastercard, is building competitive advantages.
The Gemini card’s mix of crypto rewards, stablecoin support, and strong incentives highlights how digital assets are finding their way into everyday financial products.
The message to card issuers is unmistakable: Redesign loyalty strategies and infrastructure now or risk being left behind.
Editorial Note: Our site content is not provided or commissioned by any credit card issuer(s). Opinions expressed on CardRates.com are the author's alone, not those of any credit card issuer, and have not been reviewed, approved, or otherwise endorsed by credit card issuers. Every reasonable effort has been made to maintain accurate information; however, all credit card offer details, including information about rewards, signup bonuses, introductory offers, and other terms and conditions, is presented without warranty. Clicking on any offer on CardRates.com will direct you to the issuer's website, where you can review the current terms and conditions of the offer.
About the Author