An Honest Review of the Milestone® Mastercard® with Cashback Rewards: Accessible and Unsecured
An unsecured account for subprime borrowers who want to start repairing their credit fast.
By: Erica Sandberg
Erica Sandberg, Finance Expert
Erica Sandberg is a consumer finance expert and journalist whose articles and insights are featured in publications such as the Wall Street Journal, Reuters, MarketWatch, Forbes, and MSN Money.
An experienced media host, she's led many financial programs, including her podcast, "Adventures With Money." She's appeared on Fox, CNN, "EconTalk" and "The Dr. Drew Podcast," and has been the resident money and credit authority for KRON-4 News in San Francisco for more than 10 years.
She's also the author of "Expecting Money: The Essential Financial Plan for New and Growing Families" and recipient of the 2024 Financial Literacy and Education in Communities (FLEC) Award for National Excellence.
Jon leverages 15-plus years of journalism expertise to inform financial consumers about emerging trends and companies making an impact in the industry. He is most knowledgeable in the areas of budgeting, credit card rewards, and responsible credit use. Jon has a passion for writing and editing, and his articles have appeared in publications produced by The New York Times.
Ashley Fricker has more than a decade of experience as a finance contributor and editor, and has specialized in the credit card industry since 2015. Her credit card commentary is featured on national media outlets that include CNBC, MarketWatch, Investopedia, and Reader's Digest, among many others. She has worked closely with the world’s largest banks and financial institutions, up-and-coming fintech companies, and press and news outlets to curate comprehensive content and media. Ashley holds a bachelor's degree in multimedia journalism from Florida Atlantic University.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
I can’t count how many times I heard this when I was working as a credit counselor:
“I have terrible credit, but how can I make it right without getting a card? No one will give me a chance!”
I felt their pain. There are so many reasons people have bad credit, but when they want to repair it, they’re frustrated with the lack of options. They feel stalled.
Watch on
The good news is that some credit cards are designed specifically for people who want to get ahead, and among them is the Milestone® Mastercard® with Cashback Rewards. This account can be beneficial to people who want to improve their credit without having to save for a security deposit.
Here, I’ll cover everything from how this card works to the qualification expectations and its terms and conditions. You can earn rewards as you charge, but there are considerable costs involved.
However, if you handle the Milestone® Mastercard® with Cashback Rewards in just the right way, you can use it to repair damaged credit, which will expand your opportunities.
What to Expect From the Milestone® Mastercard® with Cashback Rewards
First, recognize that the Milestone® Mastercard® with Cashback Rewards is for people with subprime credit.
Disclosure: When you apply through links on our site, we often earn referral fees from partners. For more information, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation for referrals for many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across CardRates.com (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Underwritten by the Bank of Missouri and managed by Concora Credit, consider it a tool that can help you get over the bad credit hump as you use it to make purchases.
How to Earn and Redeem Cash Back
One of the most attractive aspects of this card is that you can earn cash back as you charge. These rewards are essentially a rebate on the things you buy.
There are two rates to know about.
You will earn 5% cash back on the first $5,000 that you spend on gas with this card each year. That’s pretty good, especially with gas prices so expensive these days. If you hit that threshold, your cash back rewards for this category alone total $250.
0%5%Cash Back Rate on the First $5,000 You Spend on Gas
After hitting that $5,000 ceiling, the earnings rate drops to 1%, which is the flat-rate percentage for all other purchases you make with the card.
As for redeeming the cash you’ve earned, the Milestone® Mastercard® with Cashback Rewards works in a different way than traditional rewards cards. There are no shopping portals for which to spend on travel or entertainment expenses, nor can you cash your rewards out and walk away with the money, or use them as a statement credit.
Instead, your earned rewards will be applied to your account balance, reducing your bill so you end up paying less than you charged. I like this system because it's automatic and takes the guesswork out of the equation.
Optional Credit Protection
When you apply for the card, you have the option to enroll in Milestone® Credit Protection. It's a type of insurance that can cover you against such financial emergencies as involuntary job loss and disability.
As long as the hardship is a qualified event, the credit protection will kick in and cover at least the minimum payment for a specific number of months. Essentially, it can offset the damage that missed payments and defaults could have on your credit reports.
It will cost you, though. You’ll be charged $1.49 for each $100 balance on your monthly statement. So if you owe $500, the fee will be about $7.45; if your balance is $1,000, expect it to be around $14.90. But if you pay your bill in full every month, it's $0.
The credit protection is not required, but if you do get it and want to cancel, you can.
Depending on your circumstances, it may or may not be worth the price. For example, if you have money in a savings account that you can tap into, you may not want the protection, but the choice is yours.
Tri-Bureau Credit Reporting
Remember, the purpose of the Milestone® Mastercard® with Cashback Rewards is to help push your credit scores upward. That means making sure your consumer credit reports are filled with the type of information that helps your credit scores rise.
The major credit bureaus for consumers in the United States are Equifax, Experian, and TransUnion. If you get this credit card, it will appear on each of your reports in the trade lines section.
It will list pertinent data such as the date the account was issued, your account credit line, your monthly payment history, and your average daily balance.
As long as you always make your payments on time and pay your balance in full, you can be sure that you’re feeding positive information to your credit reports, which will be calculated into your credit scores.
When you manage your Milestone® Mastercard® with Cashback Rewards responsibly, your credit rating should improve over time.
Costs, Fees, and Possible Interest Rate
All this comes at a cost, and yes, it can be daunting. This is not a free or cheap credit card, and it starts with a hefty annual fee. That amount will be added to your account balance as soon as you open it, too.
This means you’re starting out with debt. The $1,000 credit limit will be cut down to $750. Prepare to pay the fee off right away so you can have the full credit limit available to you.
After having this account for 12 months, the annual fee drops to $99. Better, but it's still a charge that will be added to your account.
However, when year one turns into year two, another fee goes into effect. You will be charged a monthly maintenance fee of $12.50. The end result? That’s another $249 a year.
Last but hardly least is the interest rate that will be added to balances you carry over from one month to the next. The Milestone® Mastercard® with Cashback Rewards has an APR of 35.90% on both purchases and cash advances.
That makes carrying a balance wildly expensive, especially if you max the account out and only pay the minimum. Do so, and it would take roughly 8 years to fully pay off the debt, and nearly $1,700 in interest fees alone.
For this reason, it’s best to send the full amount due before interest accrues. You have a 25-day grace period to pay your bill in full.
The Guaranteed Credit Limit & Potential for Increases
Although the costs connected to the Milestone® Mastercard® with Cashback Rewards are daunting, they exist to mitigate risk. This card offers a guaranteed unsecured credit limit of $1,000. That's substantial, especially for people with subprime credit and, therefore, considered risky borrowers.
Payment history is the most important factor in a FICO Score, followed closely by credit utilization, which is how much of your credit you have open. To earn a high score, your credit utilization ratio should be low because it indicates you aren’t borrowing to make ends meet.
Having $1,000 at your disposal not only helps your ability to pay for expensive things without hitting your limit, but it can also be favorable to your credit scores.
For example, if you charge $300 worth of gas every month and your credit limit is $1,000, you still have 70% of your credit line available to you. That's healthy for a credit score. But if you constantly pay the bill off (and on time), it will have an even greater scoring impact.
Unlike some other subprime credit cards, the Milestone® Mastercard® with Cashback Rewards doesn’t offer automatic credit limit hikes after six months to a year of responsible use.
So, you’ll either have to wait until the issuer deems you worthy of an increase or request one yourself. I recommend using the card responsibly and waiting at least six months before requesting an increase.
Mobile App & Customer Service
Chances are, you’ll be doing the bulk of your credit card management either online by logging into your account or through the mobile app. Both the website and the app enable you to conduct this business 24 hours a day, 7 days a week.
Hopefully, you won't have anything too complicated to deal with. If you have extra questions or special needs, you may get frustrated with the basic functionality and turn to phone support. Unfortunately, customer service may be lacking.
I conducted a thorough review of these services and found some consistent complaints. Chief among them are slow payment processing times, with many cardholders saying it can take a week for payments to post. Others mentioned sudden account closures and being surprised by fees.
The Concora Credit App
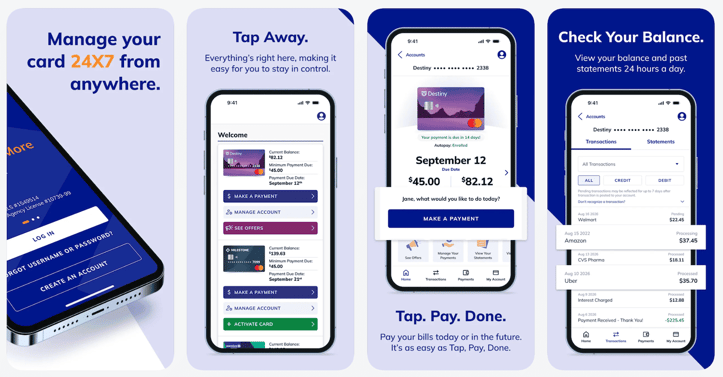
Since Concora Credit manages the Milestone® Mastercard® with Cashback Rewards, you will be using its free mobile app. When you download it to your device, you can activate your card.
Once done, you will see your account on the app and can submit and schedule payments, review your transaction history, and update your personal account information.
You can schedule payments and track your account with the Concora Credit App.
Outside of that, the app doesn’t do much. There are no special budgeting tools to keep your spending on track, or push alerts to let you know when a payment is due or when suspicious activity is detected on your account.
Still, if all you want to do is review your transactions, check your balance, and pay your bill, the app is fine.
Service Channels and Responsiveness
On a Tuesday afternoon at around 1:00 PM, I called two different numbers in succession: 1-866-502-6439 and 1-800-305-0330. Both went to the same call center.
The first time I called, there was a wait time of about one minute. Not bad. A woman picked up, and I think she said her name was Angie, but the connection was very crackly.
I asked Angie to direct me to the specific website page associated with the Milestone® Mastercard® with Cashback Rewards, and she told me to go to the general Concora website. I then asked her to tell me more about the account, including the fees, but she said she did not have that information.
After that brief conversation, I called again and spoke with a different representative. As with the first, the connection wasn’t good, and I couldn't understand the name she gave. Still, I tried. I explained what I was looking for, and she said she couldn't help me. That conversation lasted about 30 seconds.
What You Need to Qualify
Obviously, the point of this card is to help people repair their credit history. You won’t be automatically turned down if you have delinquencies, collection activity, or even a bankruptcy on your credit reports. It may even be right for people who are just starting out and don't have any credit history at all.
Therefore, the qualification requirements for the Milestone® Mastercard® with Cashback Rewards are quite forgiving. Since it's an unsecured account, you also don’t have to put down a cash deposit.
You do need to be at least 18 years old, have a valid Social Security number, and a physical US address. A minimum credit score of 500 is best, but it's not set in stone.
What is necessary? A way to pay. You will need to provide valid employment information and have enough income to afford the monthly minimum payments. If you already owe a lot of money on other accounts, those balances and minimum payments can affect your eligibility.
Although you aren’t expected to have good credit, if you had a Milestone account before and it was charged off because you didn’t pay your bill, you may be instantly rejected.
How to Apply (Step-by-Step)
There is no prequalification process for this credit card. So, if you are interested in it, you're going to have to jump right to the application.
That’s exactly what I did, and here’s what I found:
Section 1: Read About the Card’s Benefits
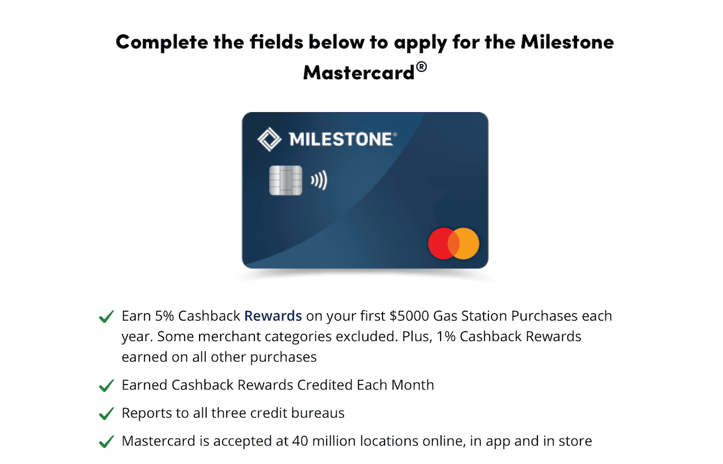
Here I see an invitation to apply for the account. There is an image of the Milestone credit card with a Mastercard logo.
I also see checkmarks for various benefits that are associated with this card. It shows that I can earn 5% cashback rewards on the first $5,000 of my gas station purchases on a yearly basis, then 1% percent cashback on everything else.
I see that my cash back rewards will be credited to my account on a monthly basis.
I also see that this account will be reported to all three credit bureaus and that Mastercard is accepted at millions of locations.
This is one long form, so I carry on to the next section.
Section 2: Personal and Income Information
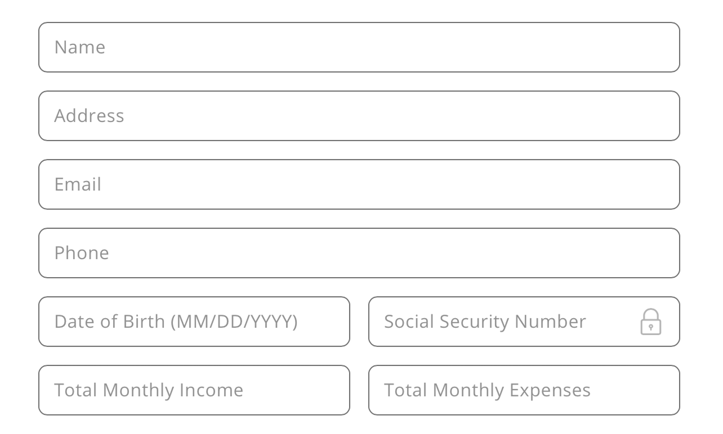
I see a series of boxes where I enter my name, address, email, phone number, birth date, Social Security number, and my total monthly income expenses.
I complete them and then continue to scroll down.
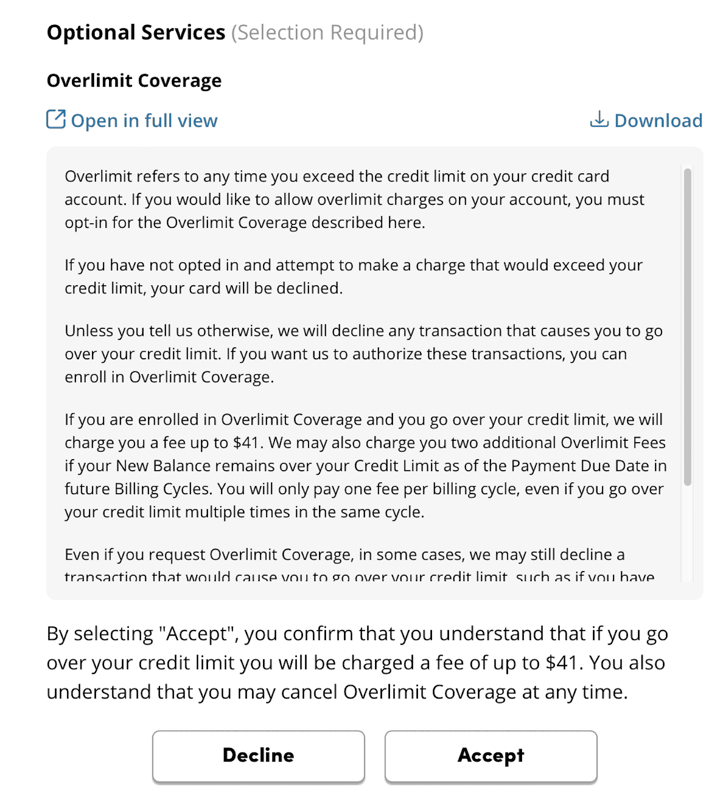
Section 3: Accept or Decline Optional Overlimit Coverage
Now I see information about an optional service for Overlimit Coverage. A light grey scroll box allows me to read about this service, which explains what it means to go over a credit limit and how this protection works.
Two buttons are at the bottom, one that says “Decline” and another that says “Accept.” If I accept, I will be confirming that I understand that if I go over my credit limit, I will be charged a fee of $41.
I click “Decline” and continue down the page.
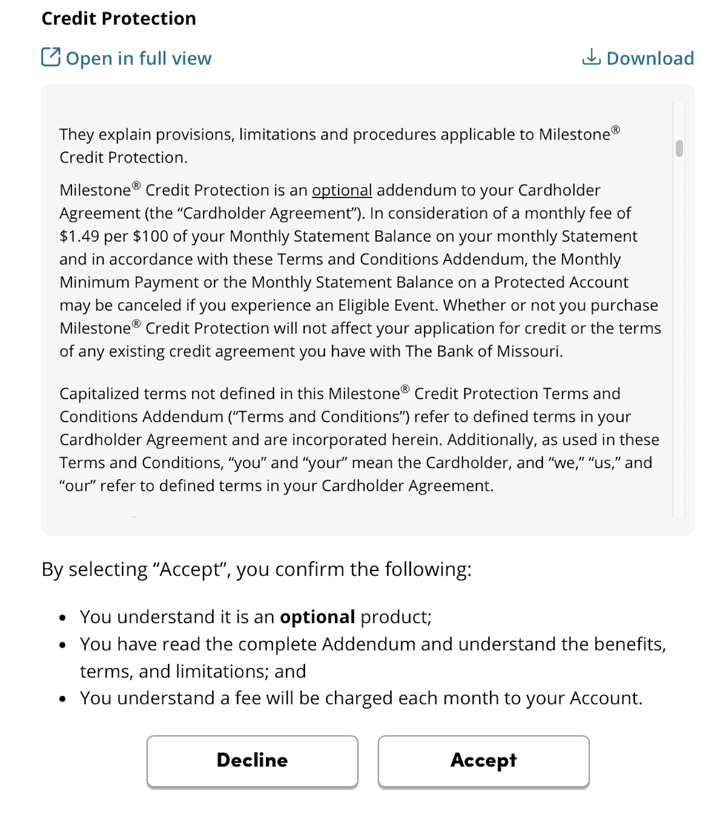
Section 4: Credit Protection Coverage Opt-In
Here is where I see information about the Credit Protection coverage. In a light gray box, I read that this is optional and the monthly fee will cost me $1.49 per $100 of my monthly statement balance.
Two buttons are at the bottom, one says “Decline” and the other says “Accept.” I see that if I accept the coverage, I am confirming that I understand this is optional, I have read all about it, and understand that the fee will be charged on a monthly basis.
I click “Decline” and continue down the page.
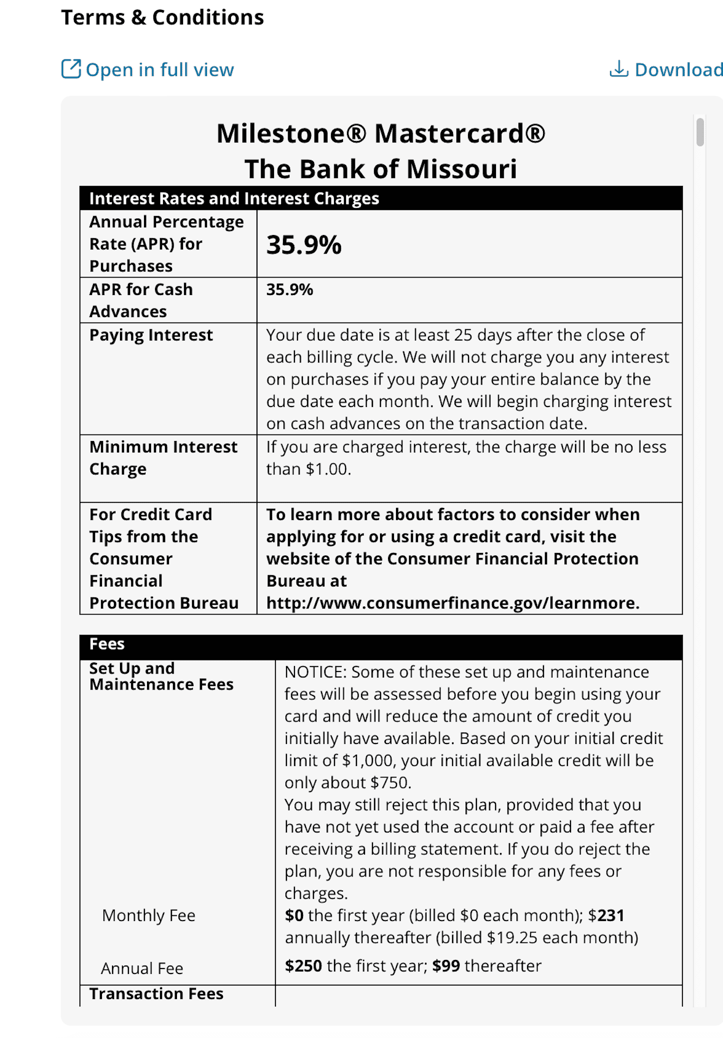
Section 5: Go Over the Terms & Conditions
Now I have arrived at the “terms and conditions” section of the application. A scroll-down box begins with a notation that the Milestone® Mastercard® with Cashback Rewards is issued by the Bank of Missouri.
The first term indicates, in large and bold font, that there is an APR of 35.90% for purchases. Under that, it shows the same APR for cash advances, but in a smaller font.
I read through all the rest of the terms and conditions and moved on to the next section.
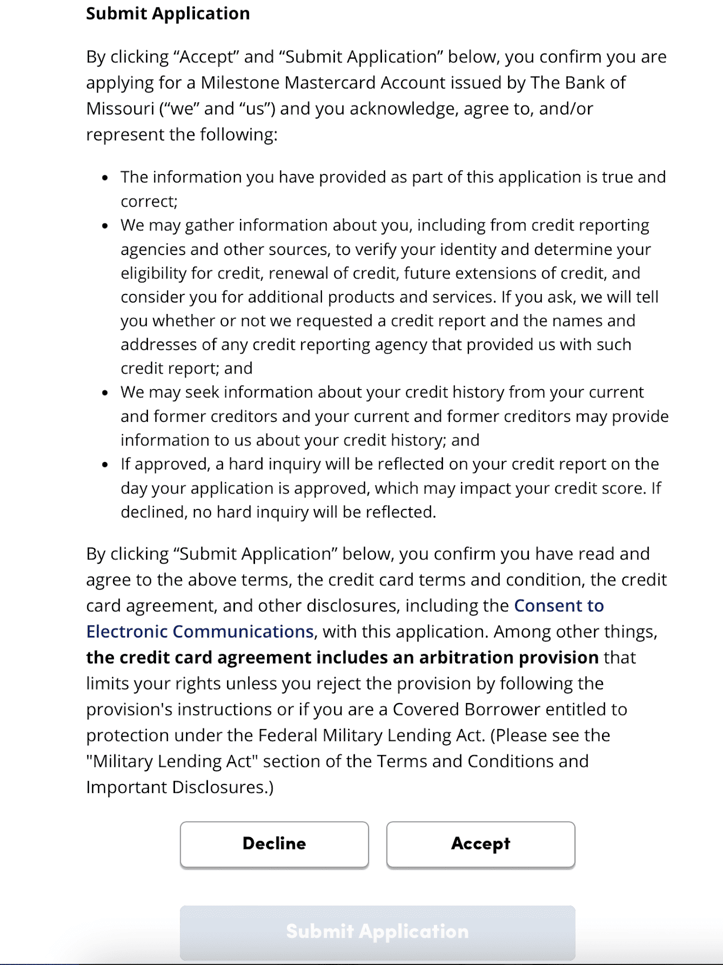
Section 6: Accept Terms and Submit Application
This is where I see the Submit Application area of the form. I read that if I click the “Accept” button at the bottom, and then click “Submit Application,” I will be confirming that I'm applying for this credit card. I also read that I am agreeing to the terms and that I am confirming that I have read them.
There is also a “Decline” button that I can push if I do not want to go through with the application. Since I am not really applying for this card, I just close out the screen.
The entire application took about eight minutes from start to finish.
Pros and Cons
The Milestone® Mastercard® with Cashback Rewards is definitely not right for everybody. It comes with some positive features, but the negatives are significant.
It will be of utmost importance to understand what you're getting into and to use it in a way that will benefit you in the long-term.
Pros
Guaranteed $1,000 credit limit
Cash back rewards, including 5% cash back rate on gas purchases up to $5,000 in spending
Account activity is reported to all three major credit bureaus
Cons
High first-year annual fee and monthly maintenance charges
No automatic credit limit increases after positive account management
You can offset problems with the Milestone® Mastercard® with Cashback Rewards by entering with the right expectations.
The fees are high, but if your credit rating is preventing you from qualifying for low-cost, high-value accounts, you can use it to build your credit.
Similar Cards Worth Considering
When you’re rebuilding credit, there are a lot of credit cards to choose from. But none of them are perfect, and if you have subprime credit, you’ll need to make some tradeoffs to offset the bank’s risk.
Here are a couple of other subprime credit card options that you may want to compare alongside the Milestone® Mastercard® with Cashback Rewards.
Disclosure: When you apply through links on our site, we often earn referral fees from partners. For more information, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation for referrals for many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across CardRates.com (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
This unsecured credit card is also designed for people with poor or limited credit. No security deposit is required, and though they aren’t guaranteed, credit limits can be up to $1,000.
The Surge® Platinum Mastercard® will report your activity to the three major credit bureaus, so as long as you use it responsibly, it will help improve your credit scores. There is a prequalification tool on the website, which can protect you from a hard inquiry if you aren’t considered a good candidate.
The regular APR is very high — as is the annual fee — plus potential monthly maintenance fees. Unlike the Surge® Platinum Mastercard®, which can offset all or most of the fees, the Surge® Platinum Mastercard® doesn’t include a rewards program, and you can’t count on getting the $1,000 limit.
Disclosure: When you apply through links on our site, we often earn referral fees from partners. For more information, see our ad disclosure
Advertiser Disclosure
CardRates.com is a free online resource that offers valuable content and comparison services to users. To keep this resource 100% free, we receive compensation for referrals for many of the offers listed on the site. Along with key review factors, this compensation may impact how and where products appear across CardRates.com (including, for example, the order in which they appear). CardRates.com does not include the entire universe of available offers. Editorial opinions expressed on the site are strictly our own and are not provided, endorsed, or approved by advertisers.
Capital One Quicksilver Secured Cash Rewards Credit Card
4.0/5.0
About this rating
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
If you're interested in rebooting your credit and want to avoid high fees, you may opt for a card that does require a security deposit. This Capital One card has some strong benefits.
You’ll be working with a popular bank, the rewards program is good, and it comes with a great app. If you use this card responsibly, Capital One may transition it into an unsecured card, and you'll get your deposit back.
However, if you don't have extra cash you can tuck away for a while, the Milestone® Mastercard® with Cashback Rewards may be preferable. Without waiting to save up enough for a security deposit, you can start using it immediately.
When you do, you can use it to increase your credit score and graduate to a card that doesn't require a security deposit at all.
Would I Recommend the Milestone® Mastercard® with Cashback Rewards?
As long as you know all of the positives and negatives associated with the Milestone® Mastercard® with Cashback Rewards, and are committed to using it in a very specific way, I would suggest looking into this account.
It can make sense if you don’t have enough cash to use as a security deposit and want to start building your credit right away. The $1,000 guaranteed credit line is definitely an asset, but you have to be very careful with upfront and ongoing fees.
If you purchase enough gas to maximize the cash back rewards, at least some of those fees will be offset. You may also like the rewards going straight to your balance, too.
This account will appear on your credit report and be factored into your credit scores, which is one of its primary benefits. As a temporary credit-building tool, it serves a purpose.
You can keep fees and frustration to a minimum by paying your bill on time and in full every month. If you want to take advantage of the credit protection plan, be sure to weigh its benefits against its cost. You can always cancel if you don't think it's worth the fees.
In the end, consider the Milestone® Mastercard® with Cashback Rewards as a product that can help jump-start a stalled credit rating.
Milestone® Mastercard® with Cashback Rewards
★★★★★3.6/5.0
Milestone® Mastercard® with Cashback Rewards
3.6/5.0
About this rating
Our experts rate credit card offers based on factors like rewards, APRs, signup bonuses, fees, and approval rates, with a focus on benefits that provide the best value. We also consider cardholder needs such as credit-building potential, issuer reputation, and customer service. Our ratings are unbiased, updated regularly, and not influenced by issuers.
Erica Sandberg is a consumer finance expert and journalist whose articles and insights are featured in publications such as the Wall Street Journal, Reuters, MarketWatch, Forbes, and MSN Money. An experienced media host, she's led many financial programs, including her podcast, "Adventures With Money." She's appeared on Fox, CNN, "EconTalk" and "The Dr. Drew Podcast," and has been the resident money and credit authority for KRON-4 News in San Francisco for more than 10 years. She's the author of "Expecting Money: The Essential Financial Plan for New and Growing Families" and recipient of the 2024 Financial Literacy and Education in Communities (FLEC) Award for National Excellence.